CACI’s logistics solutions now include a new generation of final mile location intelligence designed to help delivery operators navigate more accurately and efficiently during the final metres of a delivery journey.
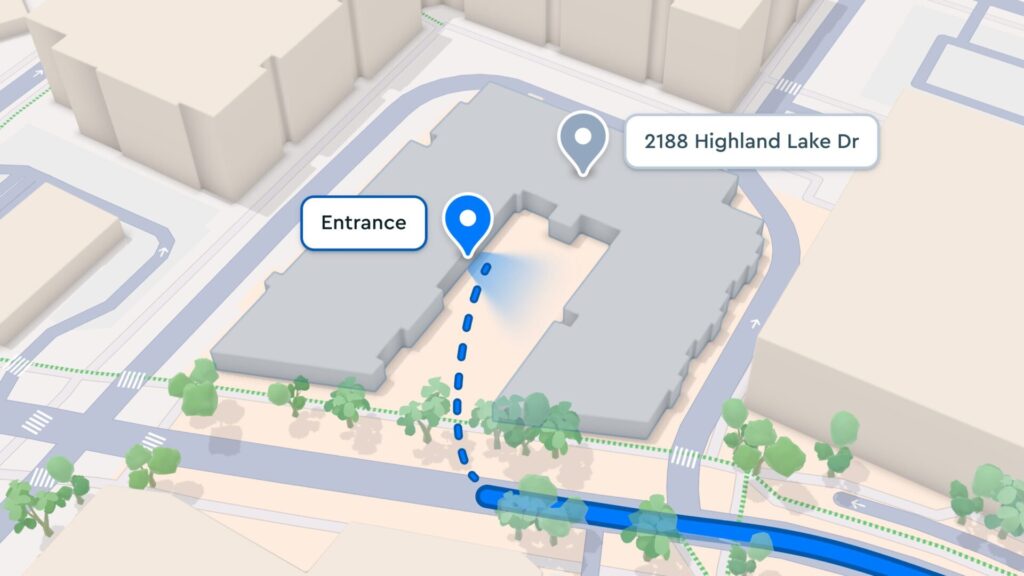
Built using patented technology and robust real-world delivery data, this innovative new product provides two critical data points for every delivery address: the precise delivery entrance and the optimal parking location.
Together, these data points guide drivers to the right place, reducing uncertainty, improving route planning accuracy and enabling more precise dwell time calculations. For organisations operating at scale, even small improvements in final mile efficiency can deliver substantial operational and commercial benefits.
The challenge with traditional address-based delivery
Traditional address-based delivery is designed to locate a building, not necessarily an entry point for a delivery. As delivery networks become increasingly complex and customer expectations continue to rise, this gap creates challenges for drivers and customers alike.
This can be particularly ineffective in locations such as:
Buildings with multiple entry points
Large complexes
Newly developed areas, where the address alone lacks the precision necessary for a smooth final delivery
University campuses
Hospitals
Gated estates
In these environments, drivers can spend valuable time searching for suitable parking, locating the correct entrance or navigating complex access arrangements. As a result, delivery times increase and route optimisation is compromised, affecting service levels and operational efficiency.
What difference will this make for last mile delivery?
Exceptional location accuracy
Through rigorous testing against other major available data sources, this new solution has demonstrated an exceptional level of accuracy. By helping drivers consistently reach the correct destination faster, route performance improves and delivery schedules become more achievable.
Two data points for every delivery location
Traditionally, only one data point per delivery address could be supplied. CACI’s new final mile location data provides two:
Building entrance to help drivers identify the correct entry point for delivery
Best parking location to help drivers reach the optimal parking spot prior to completing the final stage of the journey.
In combination, these two data points help drivers complete deliveries more efficiently while enabling more accurate dwell time calculations. This creates a more realistic understanding of how long deliveries take and enhances route planning across fleets.
How is the data created?
The intelligence behind this solution is built using patented technology integrated into delivery applications used by many providers. The technology detects various elements, including the type of movement of the device and the strength of mobile signal. This enables the system to identify when a delivery vehicle stops to make a delivery, when a driver leaves their vehicle and when they reach the delivery point. These observations are gathered repeatedly across delivery locations and combined using advanced algorithms to determine the best parking spot and the most precise delivery door location.
The result is highly accurate final mile location intelligence based on real-world delivery behaviour rather than assumptions.
What are the operational benefits?
Lower delivery costs
Operational costs associated with excess mileage or extended time spent on locating a building or property can be reduced through more accurate location data. Organisations operating at scale can lower costs by fitting more deliveries onto each route and reducing mileage and driver time.
More predictable customer experiences
More accurate location intelligence means delivery schedules will be more realistic and operational planning will improve. This will lead to more predictable customer experiences and fewer disruptions caused by unexpected delays.
Improved driver experience
Clearer guidance and fewer delivery-related frustrations are among the primary benefits delivery drivers will experience. More achievable schedules and less time spent searching for parking or delivery entrances can boost productivity and contribute to driver retention.
Better performance in complex delivery environments
Locations with multiple buildings, entries or access points inevitably challenge delivery operations. Directing drivers to both the correct delivery entrance and optimal parking spot helps remove the uncertainty that comes with complex delivery environments.
Flexible integration for every delivery operation
Final mile location data can be integrated into your existing route planning software and logistics platforms in the best-suited capacity for your organisation. The data is available as a flat file for direct ingestion and as an API for real-time integration, making implementation straightforward across a range of logistics and route optimisation environments.
Unlock the value of better final mile location intelligence
By combining precise delivery entrance and parking location data, you can bridge the gap between an address and its actual entry point to improve accuracy, efficiency and customer experience.
CACI’s global Logistics Data suite includes addresses, locations, road speeds, driving restrictions and backdrop mapping, so your systems can run smoothly, your routes can be optimally planned and efficiency maximised. Combined with our intuitive, advanced Pin Routes software and partnership with a specialist geocoding provider, final mile location intelligence provides an even more precise foundation for last mile delivery.
Contact our experts to find out how we can help improve your delivery efficiency, enhance route planning and optimise last mile deliveries.
AI ambition is no longer the problem for most organisations: strategies have been written, platforms procured and pilot use cases demonstrated. The challenge now is translating early success into AI that can be trusted and deployed at scale.
Why? The model usually is not the blocker. The data is.
As the first blog in our series on building strong data foundations for AI, we outline the process you would take to move from AI ambition to readiness. Each blog will explore a real data fragility, why it blocks AI and what “good” looks like in practice.
Common data issues that hold AI back
Data is often hard to locate, inconsistently described, poorly governed and difficult to trust. This makes it significantly harder to use AI safely and with confidence. Simply put, bad data leads to bad AI.
Organisations rarely fail because they picked the wrong model. They fail because they overestimate how ready their data estate really is. We tend to see the same recurring failure modes:
Inconsistent naming and structure: Datasets that overlap but are described differently
Incomplete or missing metadata: Making it difficult to understand what the data represents
Unclear ownership and stewardship: No single point of accountability for data quality
Weak lineage and provenance: Limited visibility of where data originated or how it has changed
Duplication and fragmentation: Multiple versions of “the same dataset across teams or platforms.
These problems are not operational irritations; they directly affect AI outcomes:
Models are trained on inconsistent or misunderstood inputs
Retrieval systems return irrelevant or incomplete context
Outputs become harder to explain and defend, particularly in regulated environments
The result? Teams end up doing data clean-up instead of building working AI.
FAIR as a practical starting point
The FAIR Guiding Principles (Findable, Accessible, Interoperable, Reusable) were introduced in 2016 to make data easier for both humans and machines to find, share and reuse. FAIR consists of fifteen principles which aim to make data:
Findable: Ensuring data and metadata is discoverable by humans and machines.
Accessible: Data and metadata are accessible with open protocols (with authorisation and authentication applied as necessary) and metadata remains when data is no longer available to support historic auditability and provenance.
Interoperable: Data and metadata use a formal, shared and broadly applicable language, including vocabulary that follows FAIR principles. Data and metadata may reference other data or metadata.
Reusable: Domain relevant and richly described metadata should be reusable and, importantly, associated with data provenance.
What people often miss is that FAIR is not about making data easier for people to browse, but about making it easier for systems to work with. As data volume, complexity and speed increase, humans increasingly rely on computational support. FAIR ensures those systems operate reliably. Its growing relevance to AI stems from its ability to address many challenges organisations face when trying to scale AI.
This is integral if you want AI to work beyond a demo. If data cannot be reliably understood by machines, pipelines break down. Feature engineering becomes inconsistent. Joining data across the organisation becomes slow and expensive. AI systems become brittle and hard to scale.
For organisations beginning their AI journey, FAIR changes the question from “Do we have data?” to “Can our systems reliably find, understand, combine and reuse it with minimal human intervention?”
Why FAIR is necessary, but not sufficient
FAIR provides a practical foundation for describing, discovering and reusing data. It helps with some of the basics, but it does not guarantee that the data is accurate, current or fit for real-world use.
FAIR solves discoverability, not fitness
FAIR ensures data can be found, accessed and understood. This removes many barriers preventing effective data discovery and consumption, enabling trusted data reused across systems, encouraging:
Rich, structured metadata
Consistent identifiers and references
Standardised formats and vocabularies
Clear provenance and licensing.
But it does not answer key questions:
Is the data accurate and complete?
Is it current and maintained?
Is it actually suitable for the decision or process it will support?
Can it be trusted when the decision really matters?
In AI systems, poor data quality directly affects outcomes. Systems trained on incomplete or inaccurate data will learn and reproduce weaknesses. Poor data requires AI systems to resolve data issues before use, requiring more processing power and tokens, leading to less accuracy and more expensive results.
It is entirely possible to have data that is technically FAIR, but still:
Contain significant quality issues
Be poorly governed in practice
Be unsuitable for model training or inference.
From an AI perspective, FAIR-compliant data may still produce unreliable predictions, bias into model outputs or undermine confidence when it comes to AI-driven decisions. Discoverability in isolation will not make data AI-ready.
AI introduces additional demands beyond FAIR
Bad data is a problem for analytics. It becomes an even bigger problem when you add AI.
Consistency at scale: Small inconsistencies that are tolerable in reporting can significantly degrade model performance
Traceability and explainability: The ability to demonstrate how outputs were derived, particularly in regulated environments
Continuous maintenance: Data pipelines must remain stable over time, not just be discoverable at a point in time
Operational integration: AI also depends on data being available inside the tools and processes people actually use.
FAIR supports elements of this, particularly around metadata and provenance, but on its own, it cannot check for data accuracy, offer ongoing data management, monitor data quality slips or integrate data into production systems.
Without these, you cannot rely on the data when AI moves into real-world use.
Governance, stewardship and architecture still matter
Organisations that successfully move beyond pilots know FAIR is only the starting point. They also prioritise:
Clear responsibility for maintaining data accuracy and usability
Rules and controls that manage risk without slowing delivery
Ongoing work to improve and maintain data quality
A technical set-up that lets data move consistently between teams and tools.
Without these, FAIR initiatives can stall. Metadata may be defined but not maintained. Standards may exist but not be adopted consistently. Catalogues may be populated but not trusted.
Case study: Enabling FAIR foundations for a public sector client
The challenges described so far are not theoretical, they are typical of large, data-rich organisations operating in complex, regulated environments.
CACI worked with a public sector client, producing terabytes of data daily to address these challenges by establishing a standardised metadata model aligned to FAIR principles and tailored to organisational and domain needs.
Hundreds of datasets were produced and consumed across different domains, supporting everything from operational to long-term analytics workloads for public and private sector consumption. These datasets vary in structure, purpose and lifecycle, ranging from highly-structured, rapidly changing, high-volume data to bulk, unstructured, long-lived records.
Before the introduction of standardisation, this scale and diversity created familiar issues:
Difficulty finding relevant data across the estate
Inconsistent ways of describing datasets and their context
Challenges understanding lineage, provenance and appropriate use
Barriers to interoperability, particularly with international partners.
Applying FAIR through metadata standards
A standard metadata record format was defined using JSON to create a consistent, machine-readable structure for describing datasets across the organisation. This gave the client a practical way to put FAIR into use:
Findable: Metadata was structured to support discovery based on key attributes such as temporal range, spatial coverage, data type and source. This streamlined finding data without depending entirely on manual search.
Accessible: Access controls were incorporated into the metadata model, allowing datasets to be discoverable even where access was restricted, for example, for sensitive domain-related data. This reflects a common requirement in government contexts: keeping the right controls in place while still helping people find what exists.
Interoperable: Metadata was aligned to international standards, enabling data to be shared and understood across organisational and national boundaries. This is a concrete example of interoperability beyond a single organisation.
Reusable: The inclusion of provenance, lineage and structural metadata (such as measurement units and scientific context) supported reuse across different use cases and user groups.
Beyond FAIR: Organisational and technical change
For this client, implementing FAIR required:
Collaboration across stakeholders to agree upon common definitions and structures
Balancing standardisation with flexibility, ensuring the model could extend over time
Embedding metadata practices into existing processes, rather than treating them as a separate activity.
Rolling out the new standard resulted in a more consistent and user-friendly data discovery experience, improving on previous data product catalogue attempts seen through increased consumption and fewer queries from internal and external consumers. It also re-focused governance on policies that have demonstrable benefit across the organisation.
How CACI can help you achieve data readiness
To help organisations tackle many of the challenges explored throughout this series, we have created a new Data Management AI Accelerator that rapidly establishes trusted data foundations through:
AI-enabled data cataloguing
Governance
Classification
Access management.
This simplifies the understanding, security and governance of data at scale. By improving data visibility, accessibility and control, you can remove some of the key barriers that prevent AI from moving beyond experimentation and into real-world adoption.
Because successful AI is not just about what you build, but whether it can be trusted, adopted and scaled.
In the next blog, we will explore how organisations can begin to assess trust at scale, from ethics to explainability, and what it takes to apply AI with confidence in real-world environments.
If you would like to understand where your organisation sits today or learn more about our Data Management AI accelerator, contact us to discuss your AI ambitions and how you can scale them.
Related resources
eBook – News
The AI playbook: How to design, deploy and deliver AI value
Whether you’re preparing for your first inspection or looking to maintain an outstanding rating, understanding how CQC inspections work has never been more important. This guide explains the inspection process, the Single Assessment Framework, what inspectors are really looking for and how to prepare your service with confidence.
This guide is written primarily for registered managers, operational leaders and provider leadership teams. It is relevant across CQC-regulated sectors, but some practical examples are drawn from adult social care; where inspection approaches or evidence differ by sector, providers should use the relevant CQC sector guidance.
What is a CQC inspection?
A CQC inspection is an on-site evidence-gathering activity used by the Care Quality Commission (CQC) as part of its broader assessment of regulated health and social care services in England. An inspection is not the same as an assessment: an assessment is the wider process through which CQC gathers and evaluates evidence, while an on-site inspection is one method it may use to collect that evidence. CQC may also gather evidence off site. See CQC guidance on how evidence is gathered.
The purpose of a CQC inspection is to ensure providers are delivering high-quality, person-centred care while complying with the Health and Social Care Act 2008 (Regulated Activities) Regulations 2014. Rather than assessing paperwork alone, inspectors evaluate how policies, leadership and governance translate into positive outcomes for people receiving care.
CQC inspection at a glance
Before diving into the inspection process, it’s worth understanding why CQC inspections have become increasingly important for health and social care providers across England. According to the Care Quality Commission’s overview of how it regulates providers, the CQC oversees tens of thousands of health and adult social care services, with every registered provider subject to ongoing assessment and potential inspection. Meanwhile, the latest Skills for Care workforce report shows that England’s adult social care sector employs more than 1.7 million people, highlighting the critical role that workforce quality plays in delivering safe, effective and well-led care. At the same time, Office for National Statistics population projections indicate that demand for health and social care will continue to rise as England’s population ages, placing increasing pressure on providers to strengthen governance, improve quality and demonstrate continuous compliance.
Sector context matters. CQC regulates very different services, and the evidence, terminology and inspection activity that are relevant to a care home may differ materially from those used in hospitals, mental health services, primary care, community services, ambulance services or dentistry. Providers should therefore interpret the practical examples in this guide in the context of their own service type.
Why CQC inspections matter more than ever
A Care Quality Commission (CQC) inspection is far more than a regulatory requirement. It provides independent assurance that health and social care providers are delivering services that are safe, effective, caring, responsive and well-led.
For providers, inspection outcomes influence far more than compliance. They can affect:
Public trust and reputation
Local authority and Integrated Care Board commissioning decisions
Recruitment and staff morale
Occupancy levels for care homes
Business growth and sustainability
For people using services, CQC ratings provide a trusted indicator of care quality, helping them make informed decisions about where to receive care.
In recent years, CQC’s assessment approach has evolved significantly. The Single Assessment Framework (SAF) remains the current framework, but CQC is now rebuilding its approach following independent reviews by Dr Penny Dash, Professor Sir Mike Richards and the Care Provider Alliance. CQC has developed draft sector-specific assessment frameworks for adult social care, mental health care, primary and community care, and hospitals. CQC’s March 2026 update confirms that the five key questions remain central while the new frameworks are refined, piloted and tested.
For providers, the practical message is twofold: maintain readiness under the current framework, while keeping sight of the direction of travel. CQC’s 2026 pilot programme is testing the revised approach between June and October 2026, alongside—not instead of—existing inspections, before wider implementation.
The legal foundations of CQC inspections
Every provider should be familiar with the legislation underpinning inspections, including:
The CQC regulates a wide range of health and social care providers in England, including:
Residential care homes
Nursing homes
Domiciliary (home) care agencies
Supported living services
GP practices
Dental practices
Independent hospitals
Community healthcare providers
Hospices
Mental health services
Ambulance services
Although the same statutory regulator and five key questions provide a common foundation, inspection methods, evidence sources and regulatory expectations vary by sector. This distinction is becoming more important as CQC develops sector-specific assessment frameworks.
Read more about it
Your complete guide to achieving outstanding results from your CQC inspection
We take you through the CQC’s Single Assessment Framework (SAF) and examine what you’ll need to be prepared for. Download the checklist and discover how to confidently showcase your commitment to outstanding care and achieve top marks from the CQC.
One of the biggest misconceptions is that inspections begin when inspectors arrive on site.
In reality, inspections often begin long before the visit itself.
1. Continuous monitoring
Under the current assessment approach, CQC gathers information from a range of sources to decide what evidence it needs, when further assessment is appropriate and whether an on-site inspection is required. Sources may include:
Previous inspection findings
Notifications submitted by providers
Safeguarding concerns
Complaints
Feedback from people using services
Local authority intelligence
NHS partners
Workforce information
Performance indicators
This allows the regulator to build a picture of service quality over time rather than relying on a single inspection day.
Depending on the service and level of risk, inspections may be announced or unannounced.
Before visiting, inspectors may review:
Policies and procedures
Governance records
Quality assurance audits
Training compliance
Accident and incident data
Complaints
Staffing information
Medicines management records
Risk assessments
Providers who maintain organised, up-to-date records throughout the year are generally much better positioned than those trying to prepare everything at short notice.
Expert insight:
Strong documentation alone won’t secure a positive inspection outcome. Inspectors are looking for evidence that policies are implemented in practice, reviewed regularly and lead to measurable improvements.
3. During the inspection
Inspection activities typically include:
An opening meeting with senior leaders
Observations of care delivery
Interviews with managers and staff
Conversations with people using services and their relatives
Review of care records
Examination of governance documentation
Medicines audits
Infection prevention and control checks
Environmental observations
Rather than relying on a checklist, inspectors build a body of evidence to determine whether services consistently meet the Fundamental Standards.
4. After the inspection
Following the visit, the CQC analyses all available evidence before producing a draft report.
Providers normally have 10 working days from the date CQC emails the draft report to submit factual accuracy comments. The process is intended to identify factual errors or incomplete evidence; supporting evidence should relate to the position at the time of the assessment. Action taken after the inspection can be reported, but it will not normally change the judgement or rating based on the evidence gathered at the time.
It is also important to distinguish the available routes for challenge. Factual accuracy comments address errors or incomplete evidence in the draft report. A complaint concerns how CQC has carried out its work. After a rating is published, a rating process review is limited to whether CQC followed the correct quality-control process; it is not a fresh reconsideration of the evidence simply because a provider disagrees with the judgement or rating.
Where a published rating is eligible for review, CQC’s current guidance says a rating process review request must normally be submitted within 15 working days of publication and must identify how the rating process was not followed correctly.
Make sure leaders can explain the service’s highest risks, current improvement priorities and the evidence behind them.
Sample records regularly and check that written procedures match what staff actually do in practice.
Track audit, incident, complaint and feedback actions through to completion, then verify whether the change improved outcomes.
Test staff understanding through supervision, observation and competency checks rather than relying on training-completion percentages.
Keep evidence accessible and current so the organisation can demonstrate quality without a last-minute inspection exercise.
Agree clear ownership: registered managers or service leads should understand day-to-day quality and risk; nominated individuals or senior leaders should be able to demonstrate oversight, challenge and follow-through on improvement actions.
Understanding the current CQC assessment framework — and what is changing
The Single Assessment Framework remains CQC’s current assessment framework. It uses the five key questions, Quality Statements and evidence categories to support judgements about quality. However, it should now be understood as the current framework during a period of regulatory transition rather than the settled future model.
Following the Dash, Richards and Care Provider Alliance reviews, CQC accepted the need for greater clarity, consistency and sector relevance. Its current proposals move toward sector-specific frameworks, reintroduce rating characteristics and supporting key lines of enquiry, and remove scoring from the future assessment methodology. CQC has emphasised that these changes are being tested and refined through consultation and pilots before wider implementation.
Why did the CQC introduce the Single Assessment Framework?
The previous inspection model relied heavily on scheduled inspections and the Key Lines of Enquiry (KLOEs). While effective, it didn’t always provide a complete picture of how a service was performing between inspections.
The Single Assessment Framework was designed to:
Create greater consistency across different sectors.
Assess providers more continuously rather than at fixed intervals.
Make greater use of data, feedback and intelligence.
Focus on outcomes for people using services.
Reduce duplication while improving transparency.
Rather than asking providers to prepare for one inspection event, the framework encourages organisations to build quality improvement into everyday practice.
This describes the rationale for the SAF when it was introduced. CQC has since acknowledged shortcomings identified through independent reviews and provider feedback and is using that learning to develop the next, sector-specific approach.
Expert tip
Providers should avoid designing internal assurance around a single version of the framework. Focus on durable fundamentals—safe care, people’s experience, competent staff, effective governance, learning and measurable improvement—while monitoring CQC’s sector-specific guidance as the 2026 pilots progress.
The five key questions remain
The five core questions remain central under the current SAF and are also retained in CQC’s draft sector-specific frameworks:
Key question
What inspectors want to understand
Safe
Are people protected from avoidable harm and abuse?
Effective
Does care achieve positive outcomes using evidence-based practice?
Caring
Are people treated with kindness, dignity and compassion?
Responsive
Are services organised around people’s individual needs?
Well-led
Is there effective leadership, governance and a culture of improvement?
Every piece of evidence collected contributes towards one or more of these areas.
What are quality statements?
Under the current Single Assessment Framework, Quality Statements describe the behaviours, processes and outcomes CQC expects providers to demonstrate.
They replaced the previous detailed Key Lines of Enquiry (KLOEs). However, CQC’s proposed sector-specific frameworks are moving in the opposite direction: supporting KLOEs would replace the current Quality Statements and would sit alongside reintroduced rating characteristics. This proposed change is intended to provide greater clarity and sector-specific detail.
Rather than asking:
“Do you have a policy?”
Inspectors are more likely to ask:
“How does this policy improve outcomes for people using your service?”
This subtle change places greater emphasis on evidence of impact, rather than simply the existence of documentation.
For example, a medicines policy alone carries little value if there is no evidence that:
staff understand it,
competency is assessed,
audits identify issues,
corrective actions are implemented,
improvements are sustained.
The six evidence categories explained
Perhaps the biggest opportunity for providers is understanding how inspectors gather evidence.
Under the current SAF, CQC groups evidence into six categories to help build a rounded picture of service quality. Providers should treat these as part of the current approach and continue to monitor sector-specific guidance as the revised frameworks are finalised.
Policies, governance systems, audits, training records
Outcomes
Care quality indicators, improvement projects, incident trends
Observation
Care delivery, staff interactions, environmental standards
Partner feedback
Local authorities, Integrated Care Boards, safeguarding teams
Expert insight
This is why providers sometimes feel an inspection “came out of nowhere.” In reality, inspectors may already have months of intelligence gathered from safeguarding referrals, notifications, complaints, commissioners and previous inspections before arriving on site
Using feedback to demonstrate improvement
Feedback is strongest when a provider can show what changed because of it. This includes feedback from people using services, families, staff, advocates and partner organisations. Rather than simply recording surveys or complaints, leaders should identify themes, assign actions, communicate what has changed and check whether the change improved people’s experience or outcomes.
Worked example: repeated family feedback identifies inconsistent communication about appointment changes → leaders review the process and clarify responsibilities → staff are briefed and the process is updated → follow-up feedback checks whether communication has improved → the outcome is shared with staff and families.
The same principle applies to staff feedback and training. For example: a supervision theme identifies uncertainty about escalation → leaders confirm the underlying knowledge gap → targeted learning and coaching are provided → competency is observed in practice → incidents and follow-up audits are reviewed to confirm the change has been embedded.
What stronger CQC evidence can look like
One of the biggest misconceptions about CQC inspections is that more paperwork equals better compliance.
It doesn’t.
Under the Single Assessment Framework, inspectors aren’t assessing how many policies or audits you have—they’re assessing whether your systems consistently deliver safe, effective, person-centred care.
A policy is only valuable if it’s understood, followed and leads to better outcomes. Likewise, completing an audit isn’t enough unless it results in meaningful improvements.
The strongest evidence tells a clear story:
Issue identified → Cause understood → Action taken → Impact measured → Learning embedded
This is the difference between demonstrating compliance and demonstrating a culture of continuous quality improvement.
The examples below are illustrative and are not official CQC rating characteristics or a guarantee of any particular rating. CQC reaches judgements using the evidence available, professional judgement and the methodology applicable at the time of assessment.
Illustrative examples of increasingly mature evidence
CQC Domain
Basic evidence
Stronger evidence
More mature evidence
Safe
Risk assessments are completed but rarely reviewed.
Risks are reviewed regularly and actions are documented.
Risk trends are analysed, improvements are implemented proactively and incident rates reduce over time.
Effective
Staff complete mandatory training.
Staff complete training and competency assessments.
Learning is reinforced through supervision, observation and measurable improvements in practice.
Caring
Care plans are in place.
Care plans reflect people’s individual preferences and changing needs.
People and families consistently describe personalised care that exceeds expectations.
Responsive
Complaints are recorded.
Complaints are investigated and responded to appropriately.
Feedback drives measurable service improvements and is shared across the organisation.
Well-led
Governance meetings are held.
Audits, action plans and risk registers are reviewed regularly.
Leaders use governance data to drive continuous improvement, with clear evidence that learning is embedded across the service.
The CQC evidence cycle
Inspectors are looking for more than isolated documents—they want to see evidence of a continuous improvement process.
Stage
Example
Identify
A medication audit highlights recurring recording errors.
Investigate
Managers complete a root cause analysis and identify training gaps.
Improve
Staff receive targeted training and medication procedures are updated.
Review
A follow-up audit confirms a significant reduction in errors.
Embed
Learning is shared through governance meetings, supervision and policy updates.
Five areas providers should pay close attention to
The relevance and weight of evidence will vary by sector, service and inspection scope. The following are practical areas that commonly warrant close provider oversight; they should not be interpreted as a formula for achieving a particular rating.
Several examples below, such as medicines management, falls prevention, care planning and family involvement – are most directly applicable to adult social care. Providers in hospitals, mental health, primary and community care, ambulance services, dentistry and other sectors should apply the same underlying principles using the evidence and terminology relevant to their service.
1. Governance
Strong governance underpins almost every successful inspection.
Inspectors want to see:
Regular audits
Action plans
Risk registers
Board oversight
Continuous improvement
Learning from incidents
Governance is closely linked to Regulation 17, which requires providers to maintain effective systems for monitoring and improving service quality.
2. Safe care and treatment
Regulation 12 requires providers to deliver safe care while identifying and mitigating risks.
Depending on the sector, service and inspection scope, inspectors may examine:
Medicines management
Risk assessments
Infection prevention
Falls prevention
Equipment maintenance
Clinical decision-making
3. Staffing
Staffing remains one of the most scrutinised inspection areas.
Inspectors may review:
Recruitment
DBS checks
Training compliance
Competency assessments
Supervisions
Appraisals
Staffing levels
Training completion is only one part of workforce assurance. Providers should be able to show how learning needs are identified, how competency is assessed in practice, and how learning is reinforced through supervision, observation, incidents, reflective discussion and follow-up audits. A high training-completion percentage does not, by itself, demonstrate that staff can apply learning safely and consistently.
According to Skills for Care, workforce recruitment and retention remain among the biggest challenges facing adult social care providers, making effective workforce planning increasingly important.
Leadership and organisational culture are important sources of evidence under the well-led key question, although their significance will depend on the service, context and evidence gathered.
Inspectors frequently ask:
Do staff feel supported?
Can staff raise concerns?
Is learning shared?
Does leadership drive improvement?
Are people listened to?
Strong leadership evidence may include:
Open communication
Visible leadership
Learning culture
Innovation
Continuous quality improvement
These characteristics align closely with the CQC’s expectations for the well-led key question.
Common mistakes providers make
Many providers still prepare for inspections using outdated assumptions.
The most common mistakes include:
Updating policies just before inspection.
Completing audits without documenting actions.
Coaching staff instead of building understanding.
Treating governance as an annual exercise.
Ignoring complaints until inspection approaches.
Waiting for inspectors before identifying improvement opportunities.
The highest-performing providers don’t prepare for inspections—they prepare for excellent care every day.
Themes CQC inspectors may explore with staff and leaders
CQC does not use a standard interview script. Questions and lines of enquiry will vary according to the sector, the scope of the inspection, regulatory intelligence and what inspectors encounter during the visit. The examples below are illustrative and non-exhaustive; they are intended to show the themes staff and leaders may need to explain, not answers to rehearse.
Questions for registered managers
Inspectors often explore leadership, governance and continuous improvement.
Illustrative themes and questions may include:
How do you know your service is providing good-quality care?
What are your biggest risks and how are they managed?
Can you show examples of improvements you’ve made following audits or incidents?
How do you monitor staff competency?
How do you ensure people receive person-centred care?
What systems do you have in place to monitor complaints?
How do you ensure compliance with Regulation 17 (Good Governance)?
How do you encourage staff to raise concerns?
Can you provide evidence that lessons learned are shared across the service?
What improvements have you made since your last inspection?
Best practice:
Whenever possible, answer with evidence rather than opinion. For example, instead of saying “We monitor medicines carefully,” demonstrate medication audit results, action plans and follow-up audits showing sustained improvement.
Questions for care staff
Inspectors want reassurance that frontline staff understand both policies and practical application.
Illustrative themes and questions may include:
How would you recognise and report a safeguarding concern?
Where medicines are within your role, what would you do if a person refused medication?
How do you maintain dignity and privacy?
How do you support people to make choices?
What would you do if you witnessed poor practice?
How do you report an incident or near miss?
How do you know when a care, treatment or support plan relevant to your service has changed?
How do you protect people from infection?
How do you escalate concerns to managers?
Preparation should therefore focus on genuine understanding. Staff should know where to find relevant information, understand why procedures exist and be able to explain how they apply them in practice; coaching staff to deliver scripted answers is unlikely to provide reliable assurance.
Questions for people using services and families
CQC also gathers first-hand feedback from people who use services and, where appropriate, families, carers, advocates or representatives. The exact approach will vary by sector and service type.
Questions often include:
Do staff treat you with kindness and respect?
Do you feel safe?
Are you involved in decisions about your care?
Do staff respond quickly when you need help?
Would you recommend this service?
Have you ever raised a concern and was it resolved?
This feedback forms an important part of the evidence inspectors use when assessing the Safe, Caring and Responsive key questions.
Final thoughts: Great care doesn’t start when the inspectors arrive
The best providers don’t prepare for inspections; they build organisations that are always ready to be inspected.
While policies, audits and documentation remain important, modern CQC inspections focus on something much broader: whether your organisation can consistently demonstrate that people receive safe, effective, compassionate and person-centred care.
Whatever assessment framework applies, inspection readiness should not be a one-off project. The regulatory methodology is evolving, but the underlying disciplines—good governance, competent staff, listening to people, learning from concerns and demonstrating measurable improvement—remain central to high-quality care.
Every audit completed, every incident investigated, every complaint resolved and every staff member supported contributes to the evidence that inspectors see.
Ultimately, a successful CQC inspection isn’t about impressing inspectors for a day. It’s about building systems, leadership and a culture that delivers high-quality care every day of the year.
A CQC inspection is an assessment carried out by the Care Quality Commission to determine whether regulated health and social care services meet the Fundamental Standards and deliver safe, effective, caring, responsive and well-led care. Inspectors gather evidence through observations, interviews, care records, policies and feedback from people using the service to assess the overall quality of care.
During a CQC inspection, inspectors may observe care or treatment, speak with staff and people using the service, review relevant records and examine governance arrangements. The exact activity varies by sector, service type, inspection scope and the evidence CQC needs to gather.
CQC inspections can be either announced or unannounced, depending on the type of service and the purpose of the assessment. Most inspections of care homes and nursing homes are unannounced, allowing inspectors to observe day-to-day practice and gain an accurate picture of the quality of care being provided.
There is no fixed schedule for a CQC inspection. The Care Quality Commission now uses a risk-based, continuous assessment approach, meaning inspection frequency depends on factors such as previous ratings, safeguarding concerns, statutory notifications, complaints and other regulatory intelligence.
During a CQC inspection, inspectors consider whether services are safe, effective, caring, responsive and well-led. The evidence examined varies by sector and may include people’s experiences, staff knowledge, leadership, governance, risk management, records, safeguarding, clinical or care processes and evidence of improvement.
Providers should be able to quickly access documents that demonstrate safe, effective and well-governed care. These commonly include: Policies and procedures, care plans, risk assessments, medication records, staff training records, supervision and appraisal records, incident and safeguarding logs, audit reports, governance meeting minutes, complaints and compliments and service improvement action plans.
Inspectors may also request additional records depending on the type of service and the scope of the assessment. These are illustrative examples rather than a universal document list. Hospitals, mental health, primary care, community services, ambulance services and dentistry may need to provide different clinical, operational or governance records relevant to their sector.
A CQC assessment is the broader process used to gather and evaluate evidence about quality. An on-site inspection is one method CQC may use within that assessment process; evidence may also be gathered through off-site activity and information from other sources.
The most effective way to prepare for a CQC inspection is to embed quality assurance, governance and continuous improvement into everyday practice. Regular audits, up-to-date care records, effective risk management, staff training and strong leadership all help demonstrate that safe, high-quality care is consistently being delivered.
Following a CQC inspection, the Care Quality Commission reviews all of the evidence collected before preparing a draft report. Providers are given the opportunity to identify any factual inaccuracies before the final report and inspection rating are published.
A service rated “Requires Improvement” has not consistently met the standards expected by the CQC. Providers are usually expected to implement an improvement plan, address any identified concerns and demonstrate progress through future assessments or inspections.
Yes. Providers normally have 10 working days from receipt of the draft report to submit factual accuracy comments about incorrect facts or incomplete evidence. Supporting evidence should relate to the position at the time of assessment. After publication, a rating process review is limited to whether CQC followed the correct rating process; complaints are handled through a separate route.
The Single Assessment Framework remains CQC’s current approach, using the five key questions, Quality Statements and evidence categories. CQC is simultaneously piloting sector-specific frameworks during 2026, with proposed changes including supporting KLOEs, rating characteristics and removal of scoring. Providers should therefore follow current guidance while monitoring CQC’s improvement programme for implementation updates.
Regulation 17 of the Health and Social Care Act 2008 (Regulated Activities) Regulations 2014 requires providers to maintain effective governance systems. This includes monitoring service quality, identifying risks, maintaining accurate records and continuously improving the safety and effectiveness of care.
Yes. Complaints are one of several intelligence sources used to inform CQC inspections. Inspectors may review complaints alongside safeguarding concerns, statutory notifications, incidents and feedback from people using the service to help determine where regulatory attention is needed.
Yes. Depending on the sector and service, inspectors may speak with people using services, families, carers, advocates or representatives to understand their experiences. CQC can compare this feedback with observations, records, staff feedback and other evidence.
GLP-1 medications are creating new opportunities for brands as consumers increasingly prioritise health, wellbeing and lifestyle goals.
As adoption grows, particularly following the introduction of more accessible treatment formats, spending is shifting towards products and services that support these ambitions, creating a new consumer segment with distinct needs and preferences. Organisations that understand these changing behaviours can adapt their products, experiences and marketing strategies to unlock growth opportunities.
Who is the GLP-1 consumer and what do you need to know about them?
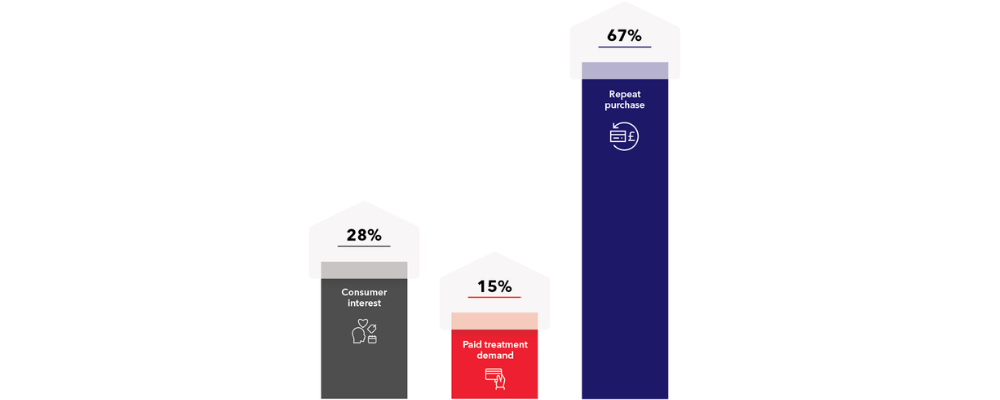
A reported 6.3% of British households have at least one GLP-1 user as of 2026, nearly triple the proportion seen in 2024 (2.3%), according to Worldpanel by Numerator. CACI’s Voice of the Nation survey, conducted across 2,000 UK adults in H1 2026, found that 13% of the UK population already self-pay for some form of weight loss product and 15% expect to pay for such products in 2026. Although these results aren’t based on GLP-1 medication use, the introduction of oral GLP-1 tablets in the UK is likely to have accelerated interest in weight loss products, as they are seen as more convenient by many.
Importantly, there is no single consumer profile for those using weight loss products. Adoption varies by age, location, household income and life stage, resulting in different spending patterns and engagement preferences across consumer groups. Understanding these nuances is critical for brands looking to identify emerging opportunities and target growth effectively.
What age groups are most engaged with weight management products?
Current users and prospective users do not always look the same, but younger adults are driving much of the demand for weight loss products. Our research found that almost a quarter (23%) of Gen Z respondents paid for a weight management product or treatment in 2025, making them the generationmost likely to self-fund weight loss treatment.
Retention is also high once people have started using weight loss products, with two-thirds (67%) of those who paid for weight loss treatments in 2025 expecting to do so again in 2026, according to our data.
As treatment becomes more accessible, adoption is likely to expand across all age groups, with younger consumers continuing to drive future growth.
What are their average incomes & affluence levels?
Observing CACI research through the lens of Acorn, CACI’s geodemographic segmentation of the UK population at postcode level, the anticipated take-up of weight management products and treatments varies significantly across consumer groups:
Upmarket Families (typical age 35+)
Prosperous Professionals (typical age range 25 – 44)
Up-and-Coming Urbanites (typical age range 18 – 34)
Limited Budgets (typical age range 25 – 49)
5%
20%
23%
20%
What weight management products are they using?
Our survey revealed that, among consumers currently using weight loss medication, tablets are the most popular option overall, chosen by 38% compared to 21% using self-administered injections. Tablet use is particularly high among those within the Limited Budgets Acorn group (48%) and Traditional Homeowners (33%). Family Renters are more likely to opt for meal replacements, with 39% choosing this option.
While respondents were not referring to GLP-1 tablets, these results suggest that greater convenience and accessibility encourage adoption among consumers who may be reluctant to use injectable treatments. With GLP-1 tablets having entered the UK market, we anticipate consumers continuing to opt for this format.
Identifying the opportunities
The rise of GLP-1 adoption tends to be associated with lower food consumption. Households with a GLP-1 user are spending an average of £418 less per year on groceries than non-user households. Brands must consider where demand is shifting to understand how these changing behaviours influence purchasing decisions and adapt products, services and experiences to meet consumers’ evolving needs.
Food & beverage
The food sector has experienced the most immediate impact from GLP-1 adoption.
As consumers become increasingly conscious of nutritional value, brands have an opportunity to move beyond volume-based purchasing behaviours and focus on quality-led consumption, such as:
Protein-rich meals and snacks
Nutrient-dense ready meals
Fresh produce and minimally processed foods
Functional foods that support wellness goals
Smaller portions with enhanced nutritional value
Meal solutions that balance convenience and health
As appetite levels change, brands that communicate nutritional benefits clearly and make healthy choices simple and accessible are likely to resonate strongest.
For retailers, category growth may increasingly come from premiumisation, nutrition-led innovation and value-added convenience rather than traditional volume growth alone.
Hospitality & quick service restaurants (QSRs)
For hospitality operators, changing consumer appetites do not necessarily mean fewer opportunities. Instead, operators may need to rethink what consumers value from eating out, such as:
Smaller-format menu options
Protein-focused and wellness-led menu innovation
Customisable portion sizes
Experience-led dining occasions
Food-and-entertainment concepts
Premium ingredients and transparent nutritional information
Success will increasingly depend on delivering experiences and value beyond portion size alone.
Health, wellness & healthcare
Health, wellness and healthcare brands are well positioned to benefit from growing consumer investment in personal wellbeing. As focus on long-term health outcomes increases, demand may grow for:
Nutritional supplements
Protein and muscle-maintenance products
Wellness coaching and lifestyle programmes
Patient support programmes
Adherence tools and digital health services
Nutritional guidance and education
Preventative health solutions
Complementary wellness products
As adoption grows, organisations that support the wider health journey, not just treatment, will be best placed to build long-term value, trust and engagement. The trend extends beyond weight management, reflecting increasing consumer investment in overall health and wellbeing.
One of the more unexpected beneficiaries of GLP-1 adoption may be the fashion sector.
As many consumers experience weight loss and body shape changes, there is often renewed demand for clothing as wardrobes need updating to reflect new sizing requirements and style preferences. This creates opportunities across:
Core wardrobe essentials
Flexible sizing ranges
Personal styling services
Occasion wear
Premium fashion purchases
In-store fitting experiences
Many consumers view weight-loss milestones as part of a broader lifestyle transformation, creating engagement opportunities with shoppers around confidence, self-expression and personal identity.
How organisations can respond to these changes
Leading brands will:
Use data and consumer intelligence to identify adoption hotspots and growth audiences
Develop nutrition-led product ranges
Clearly communicate health and wellness benefits
Offer greater flexibility in portions, formats and pricing
Invest in personalisation and targeted marketing
Create experiences that deliver value beyond the core transaction
Key takeaways
Understanding today’s weight management consumers, and how their behaviours may evolve as GLP-1 treatments become more accessible, will be critical for organisations looking to stay ahead of changing market dynamics.
The opportunity is significant. The market is being driven by young, loyal, repeat consumers who are increasingly health conscious. Brands that position themselves well now will reap lasting benefits from these innovative medications.
Combining consumer, demographic and location data, they generate a richer understanding of consumers, where they live, their behaviours and lifestyle trends that shape their decision-making. These insights can help identify and understand GLP-1 users, their habits and potential implications for consumer spending and product preferences.
By identifying these emerging audiences, you can make better-informed decisions around product development, location strategy and investment.
Consumer spending habits on cosmetic and weight-loss treatments are shifting, driven by young adults. Our blog takes a closer look.
Continuing on from our previous blog on price sensitivity among healthcare consumers, we wanted to explore the ways in which consumer spending habits are evolving. The data is again based on our H1 Voice of the Nation survey, a poll of 2000 UK-based adults.
In this blog, I want to explore the way in which consumer spending habits are changing across the cosmetic and weight-loss treatment market.
Key insights from the survey
15% of consumers expect to pay for weight-loss treatments in 2026, up from 13% in 2025.
Repeat usage is exceptionally high, with 67% of weight-loss treatment users planning to purchase again.
Gen Z and Millennials are driving demand.
Gen Z and Millennials are shifting consumer behaviour
We can clearly see an upward trend in spending on weight-loss treatments as new products, notably GLP-1s, have arrived onto the market. It has risen 2% year-on-year. Spending on weight loss treatments is overtaking spending on other cosmetic treatments, with spending on those dropping 2% over the same period: 14% of respondents in 2025 expected to pay for cosmetic treatments, decreasing to 12% for 2026.
With weight-loss treatments starting to drive demand, the retention rates for such products are impressive. Two-thirds (67%) of those who paid for weight-loss treatments in 2025 also expected to do so again in 2026. This is the highest repeat spending observed in the data among different types of private treatment.
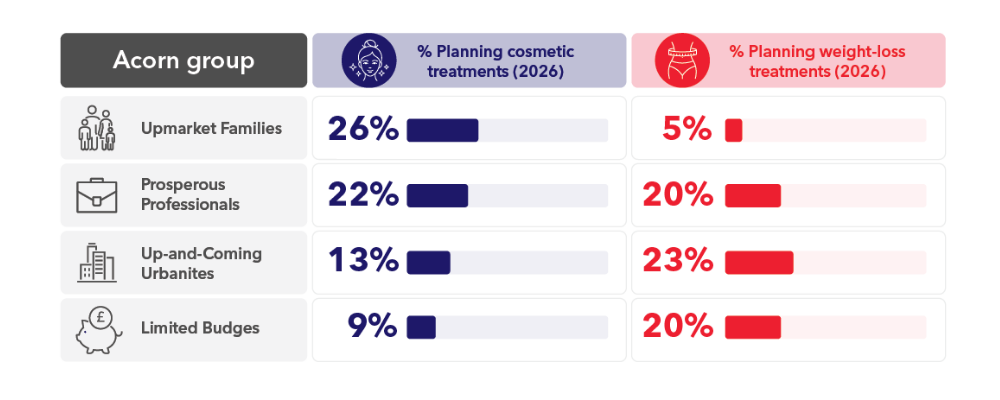
Observing the survey data through the lens of Acorn, CACI’s geodemographic segmentation of the UK population at postcode level, the anticipated take-up of cosmetic and weight-loss treatments varies wildly. The results demonstrate the extent to which age is a greater factor than affluence when it comes to spending in this area. Observing the survey results through specific Acorn groups:
Among Upmarket Families, 26% planned to pay for cosmetic treatments, but only 5% for weight loss
Within Prosperous Professionals, 22% would pay for cosmetic treatments and 20% for weight loss
Up-and-Coming Urbanites exhibit the opposite behaviour, with 13% looking to pay for cosmetic treatment but 23% for weight loss
At the lower end of the affluence spectrum, 9% of the Limited Budgets group would pay for cosmetic treatment but 20% for weight-loss treatments
It is clear that consumers are increasingly viewing healthcare as a growing concern and an ongoing service. The repeat spending on weight-loss treatments emphasises how consumers, particularly younger adults, are willing to invest in such products.
How can healthcare providers respond to this?
From the high retention rates in the weight-loss results, the most successful healthcare organisations will build continuous engagement models similar to those used by digital wellness brands. This includes the deployment of mobile apps which offer support and engagement between appointments or to track progress. When it comes to weight loss, being able to offer real-time results tracking and digital coaching can facilitate consumers realising the benefits of such products, which will help to drive retention rates.
As we explored the impact of price and affordability in our last blog, it was clear that cost is the major driver in the uptake of weight-loss treatments. Once consumers are onboard, however, there is a clear opportunity to retain them. Loyalty offers can help to make customers feel valued, whilst success stories from other customers can help them to realise the benefits of such products.
Personalised pathways powered by analytics and consumer-driven results can also help customers to navigate product offerings and work out what works best for them, with professional support on hand from the healthcare provider. This can help with things like managing dosage and side effects.
This approach is already being adopted by leading digital healthcare providers. Speaking at CACI’s Data Summit, Numan’s Director of Analytics and Data, Max Ratcliff, explained how customer insight, predictive analytics and personalised interventions are helping to improve both patient outcomes and retention within the rapidly evolving obesity care market. By combining medication with coaching, digital engagement and data-led personalisation, providers can create experiences that keep patients engaged for longer and support better health outcomes.
Key considerations
There are key technology angles for healthcare providers to consider here:
• Remote monitoring and digital coaching • Mobile apps that support patients between appointments • Personalised treatment pathways powered by analytics • CRM-driven retention strategies and automated engagement
Consumers expect to interact with services digitally, so offering that service is important. Whilst it offers a valuable service to your customers, it can also help you better understand them and their behaviours. If someone is struggling to meet their weight-loss targets with your product, for example, you can create contact points to reach out to them. Even automated touchpoints provide value to your customers, helping to drive retention rates.
The world of GLP-1s is evolving, too, with the approval and arrival of such treatments in tablet form. Healthcare providers and brands will need to understand both the barriers to entry and motivations of different consumer groups to newly available treatments to best position themselves in this dynamic market.
CACI offers solutions to help healthcare providers drive enhanced user experiences to improve customer satisfaction. Our UX and digital design expertise help brands to refine digital touchpoints to create meaningful connections with their customers. We can help you put your customers first, by providing them with the service they expect.
The healthcare consumer is more price conscious than ever: what providers need to consider
CACI’s Voice of the Nation survey from H1 2026 polled 2,000 adults across the UK. Designed to be nationally representative, our surveys explore topics relevant to consumer markets. This most recent poll delved into healthcare; private and self-funded healthcare options such as weight-loss treatments and fitness and wellness apps. The results help us to understand current and changing attitudes to healthcare among consumers, providing valuable insights to providers in understanding and reacting to market dynamics. Here, we look at some of the key findings and what they mean for healthcare providers.
Key insights from the survey
Price/affordability is the primary driver for weight-loss product selection (51%).
There is a large gap between actual and desired wellness subscription uptake: only 8% currently subscribe to fitness/wellness apps, but potential penetration could reach 25% if affordability barriers were removed.
Younger consumers show particularly strong demand for wellness and self-funded health services.
What’s driving the uptake of weight-loss treatments?
When provided with a list of six weight-loss products, including tablets, shakes, supplements, patches and injections, 28% of respondents identified at least one that they currently use (including prescribed treatments). Among those who do use these products, there are notable gender-driven differences in the products used:
Among men, tablets were the most commonly identified (14% of all men and nearly half of all those who use any product), followed by shakes and supplements.
For women, however, the distribution is much broader, with no one type of product being used by more than 9% of respondents. In this case, shakes ranked top. There is a five-percentage-point difference in usage of tablets between men and women (just 9% for women).
Take-up of different weight-loss products is motivated by different factors, with cost being a major driver. When the 28% of respondents who use these products were further asked about what was important when deciding on which products to buy, 51% identified price/affordability ahead of brand reputation, product effectiveness, product contents (natural or safe ingredients), recommendations or reviews and ratings.
That 51% who factor in price rises to 60% among those who buy supplements. However, 50% of those who use shakes identify brand reputation and online reviews as important factors, significantly higher than for any other type of weight-loss product.
The impact of affordability on subscription apps
8% of respondents say that they currently pay for a subscription to a fitness or wellness app. This ranks lower than things like food delivery service (23%) and gaming subscriptions (16%). It’s roughly on par with news or magazine subscriptions (9%) and meal kits (7%).
There is a clear age gap in the responses: 16% of Gen Z respondents said that they pay for a fitness or wellness app subscription, falling to just 4% among Gen X respondents.
Yet, many more say that they would subscribe to them if they could afford to. Among those who don’t currently pay for a fitness or wellness app subscription, 17% aspire to, rising to 34% among Gen Z. This indicates an unmet gap between potential take-up and the actual subscription base. If those who say that they cannot afford to subscribe felt able to, the 8% would rise to 25%.
Understanding the age gap
There is a gap for providers to consider here across the private and self-funded healthcare industry. Price, at least initially, is clearly very important to consumers. With a clearer intent among younger buyers to invest in their health, it’s imperative that providers consider affordability for this demographic. They’re the most likely to buy, but they’re also the least likely to have the disposable income to justify doing so.
It’s clear that consumers are increasingly willing to invest, but premium positioning and brand reputation are not enough on their own to attract customers. Demonstration of value is just as important.
Key considerations
The gap between current and potential uptake shows that the demand already exists. Affordability, rather than awareness, is emerging as the primary blocker. Technology is lowering the barrier to entry, offering a more affordable route to market at scale. Personalised digital engagement remains crucial, as does the end-to-end customer journey. From initial offers, flexible payment plans and subscription models that offer flexibility and value, to ongoing engagement and digital journeys, there are myriad ways in which providers can retain customers.
Of course, customers also need to see tangible outcomes, so ongoing support of their journey and demonstration of results is valuable. For example, people won’t continue with a weight-loss product if they don’t actually lose weight.
Finally, the underlying takeaway from CACI’s Voice of the Nation survey is that consumers are increasingly willing to invest in their health via private and self-funded routes. Demand remains strong and appears to be growing, so there is clear potential for scaling costs across a growing consumer base.
Understanding where affordability pressures are most acute is clearly becoming increasingly important for healthcare providers. Our technology and data products are designed to help you understand the specific demographics in your market. From segmentation by age and location to the specific income groups within them, CACI supports thousands of organisations across the UK with market-specific data and insights.
Two dates matter here, and they don’t line up. The overseas care worker visa route closed to new applicants in July 2025. The first Fair Pay Agreement for the sector, the policy meant to make domestic recruitment a real alternative, isn’t due to take effect until April 2028. That’s close to three years where one of the two main levers providers have traditionally relied on for workforce supply has gone, and the other hasn’t been built yet.
These dates sit underneath decisions you’re making now: the recruitment round you’re running this quarter and the rota gaps you’re covering with agency staff next month, long before either policy has had the chance to make a difference.
What’s actually changed on sponsorship?
From 22 July 2025, care providers in England can no longer sponsor new overseas applicants for care worker or senior care worker roles. The Home Office has confirmed transitional arrangements will run until 22 July 2028, allowing existing sponsored workers to extend their visas or switch employer, and reserving the right to bring that closing date forward. The effect on applications has been immediate: Health and Care Worker visa applications are down 54% year-on-year, and 92% below the November 2023 peak.
Workers already on these visas still cannot bring dependants, a restriction in place since March 2024 that continues to weigh on retention as much as recruitment. For providers, the practical position now is that overseas recruitment is limited to in-country switching: workers already here on other visa types who’ve worked for you for at least three months. Building a workforce plan around new arrivals from abroad is no longer realistic.
Why the Fair Pay Agreement fix is further off than it sounds
The Adult Social Care Negotiating Body, tasked with agreeing the sector’s first Fair Pay Agreement, is expected to be established via regulation later this year. Negotiations don’t start until autumn 2027 and the agreement itself isn’t due to take effect until April 2028.
The funding behind it raises its own questions. The £500 million committed so far works out at roughly 20p extra an hour per worker, according to Health Foundation analysis, against an estimate from the same organisation that £2.3 billion would be needed to bring care worker pay up to NHS Agenda for Change Upper Band 3 levels. Local authority staff are excluded from the agreement’s scope, which analysis from Personnel Today has pointed out sits awkwardly next to the Employment Rights Act’s stated aim of ending two-tier working practices in the sector.
None of this is an argument against the Fair Pay Agreement. Care work is low paid relative to its demands, and one in five residential care workers experience in-work poverty. The point is narrower: providers planning around 2028 as the date things improve should know how much weight that single year is being asked to carry, and how much of the detail is still unresolved.
Who picks up the bill if the Fair Pay Agreement funding gap isn’t managed well?
If the funding behind the Fair Pay Agreement turns out to be insufficient, the likely outcome is providers passing the cost on. The people most exposed to that are self-funders: residents and families paying privately for care, who have no negotiating body of their own.
The same pressure applies in the interim too. With overseas recruitment closed off, retaining staff and filling shifts increasingly means competing on pay in the local market, through agency use or local wage increases, before any sector-wide agreement exists to share that cost more fairly.
The three years between now and 2028 carry a real risk that the bill for both problems, recruitment and pay, lands on whoever is least able to query it.
Who picks up the bill if the Fair Pay Agreement funding gap isn’t managed well?
If the funding behind the Fair Pay Agreement turns out to be insufficient, the likely outcome is providers passing the cost on. The people most exposed to that are self-funders: residents and families paying privately for care, who have no negotiating body of their own.
The same pressure applies in the interim too. With overseas recruitment closed off, retaining staff and filling shifts increasingly means competing on pay in the local market, through agency use or local wage increases, before any sector-wide agreement exists to share that cost more fairly.
The three years between now and 2028 carry a real risk that the bill for both problems, recruitment and pay, lands on whoever is least able to query it.
What’s actually within your control right now?
Neither the visa closure nor the Fair Pay Agreement timeline is something a provider can change. What is within reach is staff retention and knowing your true cost to deliver care well enough to plan for what’s coming, rather than reacting to it.
That means having a clear, current picture of where staff time goes and what it actually costs to staff a rota properly, not an estimate revisited once a year. Providers who can see this clearly are in a stronger position to manage staff turnover now and respond to a future pay settlement with evidence rather than guesswork. This might mean absorbing the cost, adjusting fees with clear rationale or making the case to a local authority commissioner for a fairer rate.
Conclusion
The sponsorship route closing and the Fair Pay Agreement landing in 2028 happened on different timelines. The gap between them is where the pressure on providers will sit for the next three years. Providers who already have a clear picture of their costs and staffing will be in a stronger position to manage that gap than those still waiting for either policy to settle.
Where Certa fits into this
Certa is CACI’s all-in-one care management platform for adult social care providers. It is built on more than 30 years of CACI delivering workforce, case and financial management software to complex, high-accountability organisations, including the Care Quality Commission and Ofsted for inspection scheduling, alongside a long list of local authorities delivering adult social care directly.
Certa covers care planning and client records, rostering and workforce management, a mobile app for staff working in the field, a portal for clients and their families, and reporting and financial management, all from a single system.
A handful of those capabilities speak directly to the problem this piece has been describing.
On the cost side, real-time visit data captured through Certa’s mobile app, including arrival, departure and mileage, feeds directly into payable hours and timesheets without manual reconciliation. That is the staffing and time data providers need to model the cost of a future Fair Pay Agreement settlement, rather than finding out after it lands.
If that sounds like the clearer picture your service needs before the bill arrives, see how Certa can help.
Introducing AI in Certa: trusted AI care management software
Certa now includes AI care management software capabilities designed to help care providers work more efficiently, analyse complex data more quickly and reduce the time spent on administrative tasks. Built on cloud-based infrastructure, Certa leverages advanced AI services alongside your operational data to deliver improved outcomes for you and your clients.
The AI landscape is rapidly evolving and Certa’s product roadmap features ongoing ideas for the incorporation of AI for the betterment of the software and person-centred care outcomes. As with every Certa release, we work closely with our customers throughout the development process. AI is no different.
AI care management software you can trust
Trust is essential when using AI care management software. Certa’s AI only ever calls upon your data from within Certa, removing the risk of hallucination and error. This means you can rely on the accuracy of the answers Certa provides.
Every AI release within Certa is signed off by CACI’s Clinical Safety Officer and Certa is DCB0129 compliant, providing complete peace of mind when using its AI capabilities
Find important information faster
Care records often contain large amounts of information. Finding the information you need, when you need it, can be time consuming. Certa’s AI care management software tools help users identify and access important information within complex records instantly, including client risks, needs and priorities.
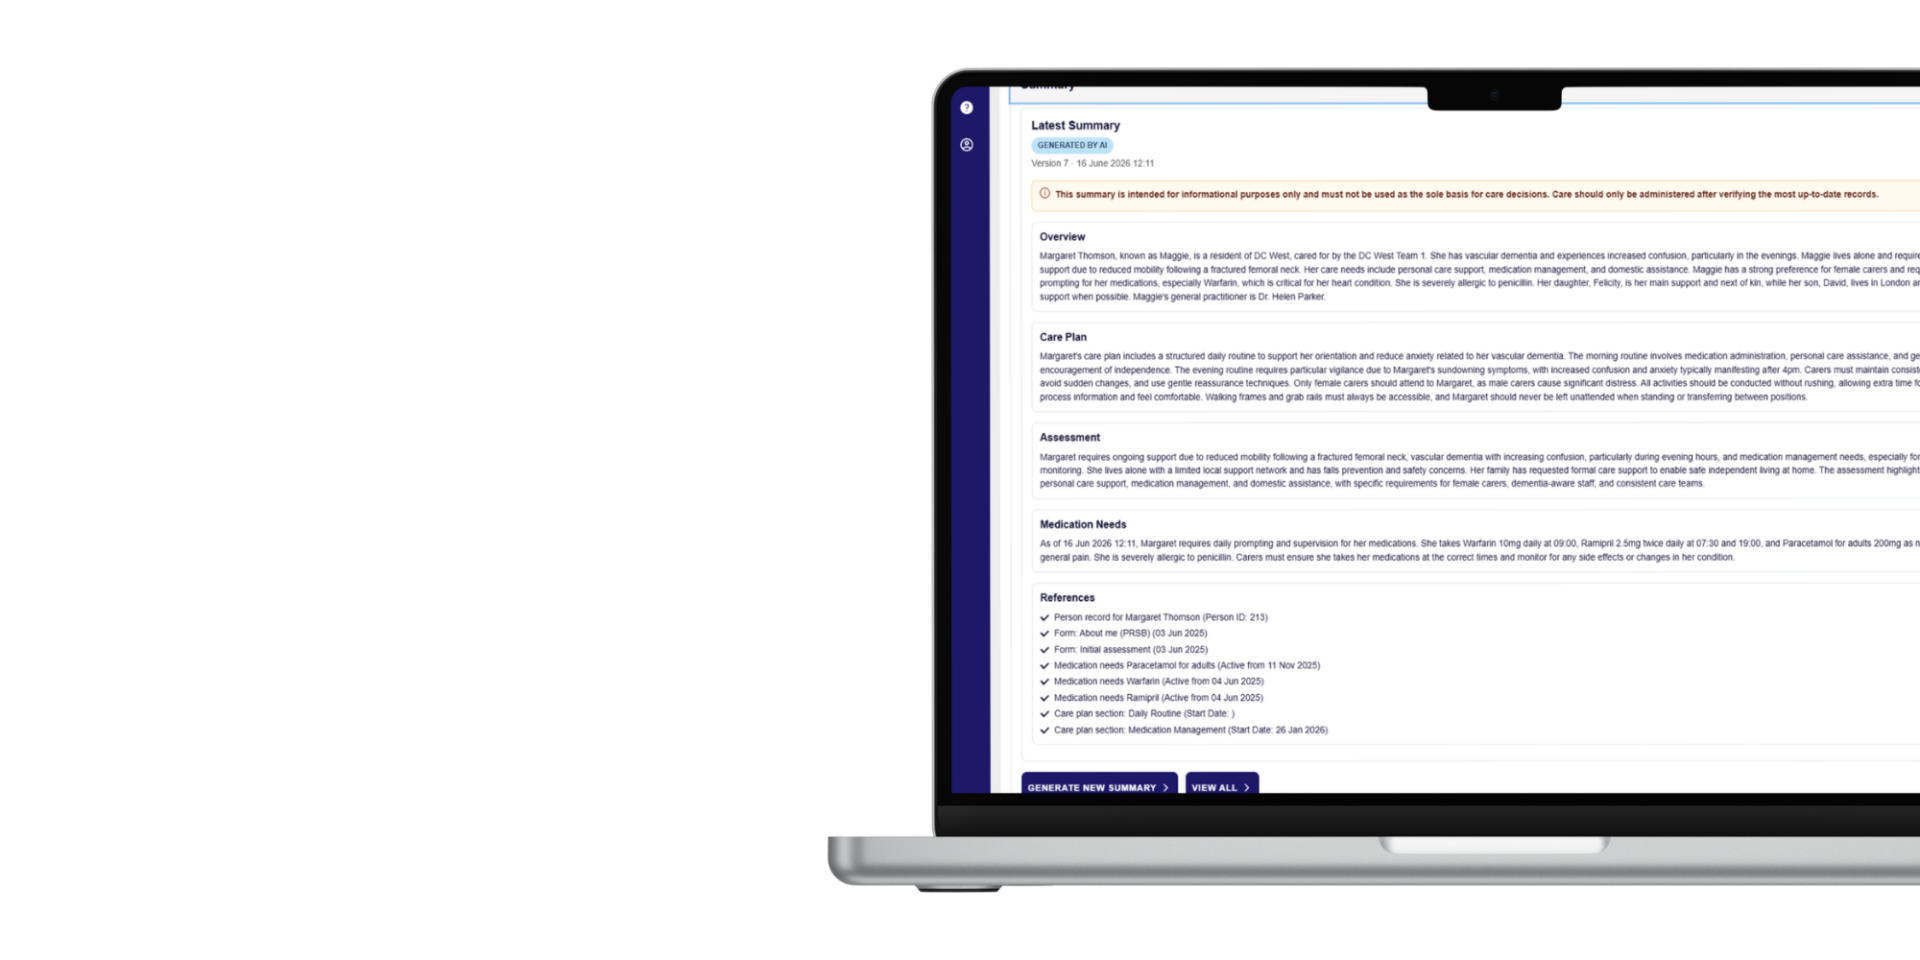
Certa’s AI client summary generates concise overviews, describing a client and their needs using information captured within their client record, assessments, care plan and medication needs. This helps users understand client needs quickly, without creating bespoke reports and sifting through data.
Reduce administrative effort
Documentation is one of the biggest drains on care workers’ time. Certa’s AI Care Notes feature, which is scheduled for release towards the end of 2026, will assist support workers in capturing care records more quickly and accurately, while also helping back-office staff keep assessments and care plans current through AI-assisted transcription and form completion. Less time on paperwork. More time on care. Without cutting corners on the record that matters.
As the data called upon only exists within your Certa system, the accuracy of its output will reduce the risk of human error. This will help to enhance the accuracy and consistency of your reports, providing trustworthy information that users can rely on, whilst at the same time reducing the administrative burden.
Smoother rostering
As well as reducing the administrative burden in report curation via AI, Certa’s sophisticated algorithms also assist schedulers in matching care workers to clients. When it comes to rostering and schedules, an algorithm offers better support than AI as there’s less interpretation of the process – your rules, your roster. This is particularly beneficial when it comes to short-term and last-minute changes. If a carer is absent from work, how can you best restructure your care services to ensure that all clients receive the care they need?
Certa can instantly suggest changes based on the availability, experience and geographic location of the carer at any given moment with the needs and preferences of the client. This reduces the time spent matching this information manually, leaving schedulers to double check suggestions reducing the impact of inevitable late changes.
Continuously evolving AI care management software
Certa can instantly suggest changes based on the availability, experience and geographic location of the carer at any given moment with the needs and preferences of the client. This reduces the time spent matching this information manually, leaving schedulers to double check suggestions reducing the impact of inevitable late changes.
Conclusion
There are understandable concerns around the use and future reliance on AI, particularly in safety critical environments such as care providers. Simply, mistakes cannot be tolerated. We’ve designed Certa’s incorporation of AI to mitigate these risks, but also to work alongside and support human care.
Care is a very human service and is not something that can ever be replaced by AI. Our intention is for it to support this human delivery by providing tools that help to keep services on track, even in times of strain. By helping to reduce administrative tasks, Certa and its AI care management software tools will free up time to be focussed on business care priorities, ultimately underpinning the delivery of outstanding person-centred care.
Retail Data Analytics: The Definitive Guide to Data-Driven Retail Growth
Antoine Senkoff
Retailers are generating and collecting more data than ever before. Every customer interaction whether it takes place in-store, online, through a mobile app, a loyalty programme or a retail media network, creates valuable information that can be used to improve decision-making.
In this environment, retail data analytics is no longer simply a reporting function. It has become a strategic capability that helps retailers understand customer behaviour, forecast demand, optimise inventory, improve marketing performance and make faster, more profitable decisions.
What is retail data analytics?
Retail data analytics is the process of collecting, integrating, analysing and interpreting retail data to improve decision-making across sales, marketing, inventory management, customer experience, pricing and operations.
By combining data from point-of-sale systems, ecommerce platforms, loyalty programmes, customer relationship management (CRM) systems, inventory management platforms and digital marketing channels, retailers can identify trends, forecast demand, optimise operations and improve profitability.
Modern retail analytics helps organisations answer four critical business questions:
What happened?
Why did it happen?
What is likely to happen next?
What should we do about it?
As retail becomes increasingly omnichannel and customer expectations continue to rise, retail data analytics has evolved from a competitive advantage into a business necessity.
Benefits of retail data analytics
Retail analytics delivers measurable value across customer experience, merchandising, operations, inventory management and profitability.
While specific outcomes vary by retailer, the business benefits are often substantial.
Improved customer understanding
Retailers generate customer data from numerous touchpoints.
Analytics helps organisations transform this information into a deeper understanding of customer behaviour.
Insights include:
Purchase history
Product preferences
Shopping frequency
Channel preferences
Customer lifetime value
Churn risk
This enables retailers to create more relevant and personalised customer experiences.
Retail analytics enables organisations to incorporate historical sales data, seasonality, promotions, economic factors, weather patterns and local events into forecasting models.
Improved forecasts help retailers:
Reduce stockouts
Avoid overstocking
Improve inventory productivity
Increase availability
Inventory optimisation
Inventory is one of the largest investments within retail businesses.
Analytics supports:
Replenishment planning
Safety stock optimisation
Allocation decisions
Assortment planning
Benefits include:
Lower inventory carrying costs
Improved stock availability
Reduced markdowns
Better working capital efficiency
More effective marketing
Marketing analytics enables retailers to understand which activities generate the greatest return.
Analytics supports:
Campaign attribution
Customer segmentation
Personalisation
Media optimisation
Audience targeting
This allows marketing budgets to be allocated more effectively.
Improved pricing decisions
Pricing remains one of the most powerful drivers of retail profitability.
Retail analytics helps organisations evaluate:
Competitor pricing
Demand elasticity
Promotional effectiveness
Margin performance
This enables more informed pricing decisions that balance competitiveness and profitability.
Faster decision-making
Modern retail analytics platforms provide near real-time visibility into performance. Decision-makers can identify issues and opportunities more quickly.
Examples include:
Emerging stockouts
Sales anomalies
Operational bottlenecks
Customer behaviour changes
Faster insights enable faster action.
Increased profitability
Ultimately, retail analytics supports more profitable decision-making. Improved forecasting, inventory management, pricing and marketing effectiveness contribute directly to business performance.
For many organisations, retail analytics becomes a strategic growth enabler rather than simply a reporting capability.
How retail data analytics works
Retail analytics is not simply about creating dashboards.
Successful analytics programmes follow a structured process that transforms raw data into actionable business intelligence.
Step 1: Data Collection
The first step is collecting data from relevant retail systems.
The most successful retailers embed analytics into everyday business processes, ensuring data-driven decision-making becomes part of organisational culture.
The four types of retail data analytics
Retail analytics can be broadly divided into four categories: descriptive, diagnostic, predictive and prescriptive analytics.
Each type answers a different business question and represents a progressively more advanced level of analytical maturity.
Understanding how these analytics types work together helps retailers move beyond reporting and towards proactive decision-making.
1. Descriptive analytics: What happened?
Descriptive analytics focuses on summarising historical performance.
It provides visibility into key retail metrics and helps organisations understand what has already occurred.
Common examples include:
Sales reporting
Revenue analysis
Inventory reports
Website traffic analysis
Customer acquisition reporting
Store performance dashboards
Typical retail KPIs include:
Revenue
Gross margin
Average order value (AOV)
Conversion rate
Inventory turnover
Stockout rate
For example, a retailer may discover that online sales increased by 12% last month or that a specific category underperformed against plan.
Descriptive analytics forms the foundation of all retail analytics programmes.
However, it does not explain why performance changed.
2. Diagnostic Analytics: Why did it happen?
Diagnostic analytics investigates the causes behind business outcomes.
It helps retailers identify patterns, drivers and relationships within data.
Common applications include:
Root-cause analysis
Promotion effectiveness analysis
Customer churn analysis
Basket analysis
Product performance analysis
Example: A retailer notices declining sales in a product category. Diagnostic analytics may reveal:
Increased competitor pricing activity
Reduced product availability
Changes in customer demand
Declining marketing effectiveness
By understanding why something happened, organisations can take corrective action more effectively.
3. Predictive analytics: What is likely to happen next?
Predictive analytics uses historical data, statistical modelling and machine learning to forecast future outcomes.
This is one of the fastest-growing areas of retail analytics as organisations increasingly adopt AI-powered decision-making.
Common predictive retail use cases include:
Demand forecasting
Customer lifetime value prediction
Churn prediction
Inventory forecasting
Workforce planning
Promotion forecasting
For example, predictive models may estimate:
Future sales demand
Likelihood of customer churn
Inventory requirements
Promotional performance
Predictive analytics helps retailers become proactive rather than reactive. Instead of responding to events after they occur, organisations can prepare for likely future scenarios.
4. Prescriptive analytics: What should we do?
Prescriptive analytics goes one step further.
Rather than simply predicting outcomes, it recommends actions that will optimise results.
Prescriptive analytics combines:
Predictive modelling
Optimisation algorithms
Business rules
Artificial intelligence
Common retail applications include:
Dynamic pricing
Inventory allocation
Assortment optimisation
Promotion planning
Workforce scheduling
Supply chain optimisation
For example, a prescriptive analytics system may recommend:
Increasing inventory in specific stores
Adjusting product pricing
Launching targeted customer offers
Reallocating marketing spend
This represents the highest level of analytics maturity and increasingly relies on AI-driven automation.
Retail data analytics framework
Successful retail analytics programmes typically focus on five interconnected pillars.
Customer analytics
Focuses on understanding customer behaviour and preferences.
Examples include:
Customer segmentation
Lifetime value analysis
Churn prediction
Personalisation
Key question: Who are our most valuable customers and how can we improve retention?
Merchandising analytics
Supports product and assortment decisions.
Examples include:
Product performance analysis
Category management
Assortment optimisation
Basket analysis
Key question: Which products should we stock, promote and expand?
Inventory analytics
Focuses on inventory efficiency and availability.
Examples include:
Demand forecasting
Replenishment optimisation
Inventory allocation
Stockout analysis
Key question: How can we maximise product availability while minimising inventory costs?
Marketing analytics
Measures marketing effectiveness.
Examples include:
Attribution modelling
Campaign performance
Customer acquisition analysis
Return on ad spend (ROAS)
Key question: Which marketing activities drive the highest return?
Operations analytics
Focuses on store and operational performance.
Examples include:
Labour optimisation
Store productivity
Supply chain analytics
Fulfilment performance
Key question: How can we improve operational efficiency and profitability?
Retail data analytics KPIs every retailer should track
Choosing the right KPIs is critical to measuring performance and identifying opportunities for improvement.
The most effective retail KPI frameworks balance financial, customer, operational and inventory metrics.
Revenue and profitability KPIs
Revenue
Total sales generated over a defined period.
Gross margin
Revenue minus cost of goods sold.
Gross margin return on inventory investment (GMROII)
Measures how efficiently inventory generates profit.
Average order value (AOV)
Average value of each transaction.
Formula:
Revenue ÷ Number of Orders
Customer KPIs
Customer lifetime value (CLV)
Estimated value a customer generates throughout their relationship with the retailer.
Customer acquisition cost (CAC)
Cost of acquiring a new customer.
Retention rate
Percentage of customers retained over time.
Churn rate
Percentage of customers who stop purchasing.
Inventory KPIs
Inventory turnover
Measures how efficiently inventory is sold.
Sell-through rate
Percentage of inventory sold during a given period.
Stockout rate
Frequency of inventory shortages.
Weeks of supply
Number of weeks current inventory is expected to last.
Ecommerce KPIs
Conversion rate
Percentage of visitors who complete a purchase.
Cart abandonment rate
Percentage of shoppers who leave without completing a purchase.
Revenue per visitor
Revenue generated per website visitor.
Return rate
Percentage of products returned.
Marketing KPIs
Return on advertising spend (ROAS)
Revenue generated per advertising dollar spent.
Cost per acquisition (CPA)
Average cost of acquiring a customer.
Customer engagement rate
Measures interaction across channels.
Measuring retail analytics ROI
One of the most common challenges facing retail leaders is demonstrating the value of analytics investments.
Every analytics initiative should be linked to measurable business outcomes.
Common retail analytics ROI metrics
Revenue growth
Examples include:
Increased sales
Higher conversion rates
Improved customer retention
Cost reduction
Examples include:
Reduced inventory costs
Lower fulfilment costs
Reduced markdowns
Productivity improvements
Examples include:
Faster reporting
Reduced manual effort
Improved workforce efficiency
Customer experience improvements
Examples include:
Higher satisfaction scores
Increased loyalty
Improved retention
Retail analytics ROI benchmark framework
Analytics Initiative
Primary Outcome
Demand Forecasting
Improved forecast accuracy
Inventory Optimisation
Reduced stockouts and excess inventory
Customer Segmentation
Increased campaign effectiveness
Pricing Analytics
Improved margins
Marketing Analytics
Higher ROAS
Supply Chain Analytics
Reduced operating costs
Personalisation
Increased customer lifetime value
The most successful retailers establish clear success metrics before launching analytics initiatives and continuously measure performance against those objectives.
Retail data analytics use cases: Where retailers create the most value
Retail analytics delivers value when insights are translated into business action.
While reporting and dashboards provide visibility into performance, the greatest benefits come from using analytics to optimise decisions across customer experience, merchandising, inventory, pricing and operations.
The following use cases represent some of the highest-impact applications of retail data analytics.
Customer analytics
Customer analytics focuses on understanding customer behaviour, preferences and purchasing patterns.
As retailers increasingly compete on customer experience, customer analytics has become one of the most strategically important areas of retail analytics.
Customer segmentation
Not all customers behave in the same way.
Customer segmentation groups shoppers based on shared characteristics such as:
Purchase frequency
Spending behaviour
Product preferences
Demographics
Channel usage
Engagement levels
Common segmentation models include:
Behavioural segmentation
Groups customers based on actions and purchasing patterns.
Value-Based segmentation
Groups customers based on profitability and lifetime value.
Lifecycle segmentation
Groups customers according to their stage in the customer journey.
Examples include:
New customers
Active customers
At-risk customers
Lapsed customers
Segmentation enables retailers to deliver more relevant marketing, improve retention and allocate resources more effectively.
Customer lifetime value analysis
Customer Lifetime Value (CLV) measures the total value a customer is expected to generate throughout their relationship with a retailer.
Rather than focusing solely on individual transactions, CLV helps organisations evaluate long-term customer profitability.
Benefits include:
Improved acquisition strategies
Better marketing investment decisions
More effective loyalty programmes
Higher retention rates
Retailers increasingly use predictive analytics to estimate future customer value and identify high-potential customer segments.
Churn prediction
Acquiring new customers is often significantly more expensive than retaining existing ones.
Churn analytics helps retailers identify customers who are at risk of disengaging or leaving.
Common signals include:
Reduced purchase frequency
Declining spend
Lower engagement levels
Increased returns
Reduced loyalty activity
Predictive models can identify at-risk customers before they churn, enabling proactive retention initiatives.
Personalisation and recommendation engines
Personalisation has become a cornerstone of modern retail strategy.
Retail analytics enables organisations to deliver:
Personalised product recommendations
Tailored promotions
Individualised marketing messages
Dynamic content experiences
Recommendation engines analyse:
Purchase history
Browsing behaviour
Product affinity
Customer preferences
to improve relevance and increase conversion rates.
As AI capabilities continue to evolve, hyper-personalisation is becoming a major competitive differentiator.
Inventory analytics
Inventory is often one of the largest assets on a retailer’s balance sheet.
Inventory analytics helps organisations improve product availability while reducing excess stock and carrying costs.
Demand forecasting
Demand forecasting predicts future product demand using historical and real-time data.
Modern forecasting models incorporate:
Historical sales
Promotional activity
Seasonality
Economic indicators
Weather data
Local events
Digital demand signals
Improved forecasting supports:
Better inventory planning
Reduced stockouts
Lower inventory costs
Increased product availability
As machine learning adoption grows, forecasting accuracy continues to improve across many retail sectors.
Inventory optimisation
Inventory optimisation focuses on maintaining the right inventory levels at the right locations.
Key objectives include:
Maximising availability
Minimising excess inventory
Reducing working capital requirements
Improving inventory productivity
Analytics supports decisions such as:
How much inventory to order
Where inventory should be allocated
When replenishment should occur
This is particularly important for omnichannel retailers operating across stores, distribution centres and ecommerce fulfilment networks.
Assortment optimisation
Retailers often carry thousands of products.
Not every product contributes equally to profitability.
This enables retailers to make more informed expansion decisions.
Catchment area analysis
Catchment analysis identifies the geographic area from which customers are likely to visit a store.
Insights include:
Customer density
Travel patterns
Market potential
Competitive overlap
These analyses support location strategy and marketing planning.
Artificial intelligence and machine learning in retail analytics
Artificial intelligence is transforming retail analytics.
Traditional analytics often focuses on reporting historical performance.
AI extends analytics by enabling:
Pattern recognition
Forecasting
Automation
Recommendation generation
Decision support
AI-powered analytics allows retailers to process larger datasets and generate insights at greater speed and scale.
Predictive analytics
Predictive analytics uses machine learning models to forecast future outcomes.
Common applications include:
Demand forecasting
Churn prediction
Customer lifetime value forecasting
Promotion forecasting
Inventory planning
These capabilities help retailers anticipate future conditions and act proactively.
Anomaly detection
AI can automatically identify unusual patterns within retail data.
Examples include:
Unexpected sales declines
Pricing anomalies
Fraud indicators
Inventory discrepancies
This enables faster issue detection and response.
Dynamic pricing
AI-powered pricing models continuously evaluate:
Demand levels
Competitor activity
Inventory availability
Market conditions
to optimise pricing decisions.
This capability is increasingly common in ecommerce and highly competitive retail categories.
Generative AI and conversational analytics
Generative AI is creating a new category of retail analytics.
Instead of relying solely on dashboards and reports, users can interact with data using natural language.
Examples include:
Which products are most likely to experience stockouts next month?
Which customer segments generated the highest profit last quarter?
Which stores have the strongest inventory productivity?
Generative AI translates these questions into analytical queries and delivers insights in plain language.
Benefits include:
Faster access to insights
Reduced dependency on analysts
Improved self-service analytics
Increased adoption across business teams
As generative AI platforms continue to evolve, conversational analytics is expected to become a standard component of modern retail analytics ecosystems.
Why AI-powered retail analytics matters
The volume, velocity and complexity of retail data continue to increase.
Traditional reporting approaches struggle to keep pace.
AI-powered analytics enables retailers to:
Analyse larger datasets
Identify hidden patterns
Improve forecasting accuracy
Automate routine analysis
Accelerate decision-making
For retailers seeking competitive advantage in an increasingly data-driven marketplace, AI is rapidly becoming a core capability rather than an optional enhancement.
Retail data analytics challenges and how to overcome them
While the benefits of retail data analytics are substantial, successful implementation is rarely straightforward. Many retailers invest heavily in analytics platforms but struggle to achieve widespread adoption or measurable business outcomes.
Understanding the most common challenges can help organisations develop more effective analytics strategies.
Data silos
One of the most persistent challenges in retail analytics is fragmented data.
Customer, inventory, marketing and operational data often reside in separate systems that were never designed to work together.
Examples include:
POS systems
Ecommerce platforms
CRM systems
Loyalty platforms
Marketing automation tools
ERP systems
Supply chain applications
When data remains siloed, retailers struggle to create a complete view of customers and operations.
Best practice
Invest in a unified data architecture that consolidates information into a centralised analytics environment. Modern platforms such as Snowflake, Databricks and Microsoft Fabric can help establish a single source of truth.
Data quality issues
Analytics outcomes depend on data quality.
Common problems include:
Missing data
Duplicate records
Inconsistent definitions
Outdated information
Inaccurate product hierarchies
Poor-quality data reduces trust in analytics and can lead to flawed decision-making.
Best practice
Establish formal data governance programmes that include:
Data quality monitoring
Master data management
Data ownership frameworks
Standardised KPI definitions
Skills and talent gaps
Many retailers face shortages of:
Data analysts
Data engineers
Data scientists
AI specialists
Analytics leaders
Without the right capabilities, organisations may struggle to translate data into business value.
Best practice
Combine internal capability development with external expertise and invest in analytics literacy across the organisation.
Lack of business adoption
Many analytics programmes fail because insights are not integrated into operational decision-making.
Dashboards alone rarely change behaviour.
Best practice
Focus on business outcomes rather than technology implementation.
Successful retailers embed analytics into:
Merchandising processes
Inventory planning
Pricing decisions
Marketing campaigns
Executive decision-making
Measuring value
Analytics investments are often difficult to justify when success metrics are unclear.
Best practice
Define measurable business outcomes before implementation.
Examples include:
Forecast accuracy improvement
Inventory reduction
Increased customer retention
Revenue growth
Margin improvement
How to choose a retail data analytics platform
Selecting the right analytics platform is a critical decision.
Technology choices influence scalability, usability and long-term return on investment.
Define business objectives first
The most successful implementations begin with business goals rather than technology requirements.
Questions to consider include:
Which business challenges are we solving?
Which decisions need better data?
Which KPIs matter most?
Technology should support business strategy—not the other way around.
Evaluate data integration capabilities
Retail environments often include dozens of systems.
The chosen platform should support seamless integration with:
POS systems
Ecommerce platforms
CRM systems
Marketing platforms
ERP solutions
Integration complexity often determines implementation success.
Assess scalability
Retail data volumes continue to grow rapidly.
Platforms should support:
Large datasets
Real-time analytics
AI workloads
Future growth
Cloud-native solutions often provide greater scalability and flexibility.
Consider user experience
Analytics adoption depends on usability.
Evaluate:
Dashboard design
Self-service capabilities
Natural language querying
Mobile accessibility
Collaboration features
A powerful platform that users avoid will deliver limited value.
Review AI capabilities
AI is becoming increasingly important within retail analytics.
The cheapest platform is not always the most cost-effective solution.
Retail data analytics implementation roadmap
Successful analytics transformations typically follow a phased approach.
Phase 1: Establish business priorities
Identify the highest-value opportunities.
Examples include:
Demand forecasting
Inventory optimisation
Customer retention
Pricing optimisation
Prioritise initiatives that deliver measurable outcomes.
Phase 2: Build a data foundation
Create a centralised data environment that supports analytics at scale.
Focus on:
Data integration
Data governance
Data quality
KPI standardisation
Phase 3: Deliver quick wins
Early success helps build momentum.
Potential quick-win projects include:
Executive dashboards
Inventory reporting
Customer segmentation
Marketing attribution
Phase 4: Expand advanced analytics
Once foundations are established, organisations can introduce:
Predictive analytics
Machine learning
Forecasting models
Optimisation algorithms
Future trends shaping retail data analytics
The retail analytics landscape continues to evolve rapidly.
Several trends are expected to shape the next generation of retail analytics.
Real-time analytics
Retailers increasingly require insights as events occur. Real-time analytics supports:
Inventory visibility
Dynamic pricing
Fraud detection
Operational monitoring
Customer engagement
As streaming data technologies mature, real-time decision-making will become standard.
Generative AI
Generative AI is changing how users interact with data. Emerging use cases include:
Conversational analytics
Automated report generation
Natural language querying
Insight summarisation
Executive briefing creation
Generative AI will make analytics more accessible to non-technical users.
Autonomous decisioning
The future of retail analytics is likely to involve increasing levels of automation.
Examples include:
Automated inventory allocation
Dynamic pricing adjustments
Personalised promotions
Supply chain optimisation
Marketing budget allocation
Human oversight will remain important, but decision automation will continue to expand.
Retail media analytics
Retail media networks are becoming a major revenue source for retailers. Analytics capabilities will play a critical role in:
Audience targeting
Campaign measurement
Attribution
Ad inventory optimisation
Retail media is expected to remain a major investment area over the next decade.
First-party data strategies
As privacy regulations evolve and third-party cookies decline, retailers are increasingly investing in first-party data assets.
Analytics will become central to:
Loyalty programmes
Customer identity resolution
Personalisation
Customer retention
Retailers with strong first-party data strategies are likely to gain significant competitive advantages.
Conclusion
Retail data analytics has evolved from a competitive advantage into a business necessity.
Retailers today face increasing complexity, rising customer expectations, growing competition, expanding data volumes and ongoing margin pressure. Organisations that can effectively transform data into actionable insights are better positioned to adapt, innovate and outperform competitors.
The most successful retailers use analytics to answer four fundamental questions:
What happened?
Why did it happen?
What is likely to happen next?
What should we do about it?
From customer analytics and demand forecasting to inventory optimisation, pricing intelligence and AI-powered decision-making, analytics has become central to modern retail strategy.
However, technology alone is not enough. Long-term success depends on:
High-quality data
Strong governance
Clear business ownership
Measurable outcomes
Organisation-wide adoption
Retailers that establish these foundations will be best positioned to unlock the full value of their data, improve customer experiences and drive sustainable growth in an increasingly data-driven future.
Frequently asked questions about retail data analytics
What are examples of retail data analytics?
Examples of retail data analytics include demand forecasting, customer segmentation, inventory optimisation, pricing analytics, promotion analysis and customer lifetime value modelling. Retailers use these analytics techniques to improve decision-making, enhance customer experiences and increase profitability.
Common examples of retail data analytics include:
Demand forecasting
Customer segmentation
Inventory optimisation
Pricing analytics
Promotion analysis
Customer lifetime value (CLV) analysis
Recommendation engines
Omnichannel customer journey analytics
These insights help retailers understand customer behaviour, optimise operations and identify growth opportunities.
What is the difference between retail analytics and business intelligence?
Retail analytics focuses on explaining performance, predicting outcomes and recommending actions, while business intelligence (BI) focuses on reporting and visualising historical data. Business intelligence helps retailers understand what happened, whereas retail analytics helps them understand why it happened, what is likely to happen next and what actions should be taken.
Business Intelligence
Retail Analytics
Reports what happened
Explains why it happened
Historical reporting
Predictive and prescriptive insights
KPI dashboards
Forecasting and optimisation
Performance monitoring
Decision support and recommendations
Descriptive analysis
Advanced analytics and AI
Most retailers use both business intelligence and retail analytics to support data-driven decision-making.
How can small and mid-sized retailers use data analytics?
Small and mid-sized retailers can use data analytics to improve inventory management, increase sales, understand customer behaviour and optimise marketing performance. Many organisations start with basic reporting tools before adopting more advanced analytics capabilities.
Common use cases include:
Tracking sales and product performance
Forecasting inventory demand
Identifying slow-moving stock
Measuring marketing campaign effectiveness
Analysing customer purchasing behaviour
Improving customer retention
Optimising pricing and promotions
By focusing on a small number of high-impact use cases, retailers can achieve measurable business value without significant technology investment.
What data sources are used in retail analytics?
Common data sources include:
POS systems
Ecommerce platforms
CRM systems
Loyalty programmes
Inventory systems
Supply chain systems
Marketing platforms
Customer service systems
Location intelligence data
How does retail analytics improve inventory management?
Retail analytics improves demand forecasting, inventory allocation and replenishment planning. This helps reduce stockouts, minimise excess inventory and improve inventory productivity.
How is AI used in retail analytics?
AI supports forecasting, customer segmentation, recommendation engines, dynamic pricing, anomaly detection and decision automation. Generative AI is also enabling conversational analytics and automated insight generation.
What KPIs should retailers track?
Key retail KPIs include:
Revenue
Gross Margin
Customer Lifetime Value
Conversion Rate
Inventory Turnover
Stockout Rate
Customer Acquisition Cost
Return on Advertising Spend
Average Order Value
Retention Rate
Beyond data residency: The real meaning of AI sovereignty
David Moss
AI sovereignty has quickly moved from being a policy discussion to a business priority.
As AI adoption gathers pace across government, critical national infrastructure and highly regulated sectors, the conversation is shifting. It is no longer just about what AI can do, but who controls it, how resilient it is and what happens when technology, suppliers or geopolitical circumstances change.
Recent global events have reinforced a question many leaders are now asking: how do you embrace the latest advances in AI without becoming dependent on technology not fully in your control?
Too often, the answer starts and ends with data residency.
Where data is stored certainly matters, but it is only one part of the picture. AI sovereignty is much broader. It means retaining control over the data, infrastructure, operations, governance and increasingly the AI models that underpin critical services. More importantly, it gives organisations the confidence that they can continue to operate, adapt and evolve without being tied to a single supplier or jurisdiction.
Impact of choice in AI sovereignty
That does not mean turning away from global technology providers.
The goal is not isolation or building everything from scratch, but preserving choice. Organisations should be able to decide where workloads run, how services evolve and how data is managed, while still benefiting from the pace of innovation delivered by leading cloud and AI platforms.
The decisions that shape that flexibility are often made long before the first AI model is deployed.
Building sovereignty into architecture
Architecture plays a central role. Modular, standards-based platforms make it far easier to replace or introduce individual services without disrupting the wider environment. Open APIs, common identity standards and interoperable integration patterns reduce unnecessary dependency and leave room to adapt as technology, policy and operational requirements change.
Data portability
The same thinking applies to data.
For most organisations, data is their most valuable asset. Keeping it portable, accessible and governed through open formats and clear ownership models helps avoid unnecessary lock-in while making future migrations or technology changes far less complex.
Identity & access
Identity deserves the same attention. It should be treated as a strategic capability rather than something that simply supports the platform. Using recognised standards gives organisations greater control over authentication and access without creating unnecessary reliance on proprietary services.
Cloud-native flexibility
Cloud-native engineering and containerisation also support these objectives. Applications designed to run consistently across public cloud, private cloud, hybrid environments or on-premises infrastructure provide greater resilience and flexibility. These are not always the most visible design decisions, but they often determine how adaptable an AI platform will be in five or ten years’ time.
Governance is as important as technology
Technology, however, is only part of the answer.
One of the biggest challenges we see is moving beyond successful AI pilots. Many organisations have demonstrated value in controlled environments but struggle to scale because governance has not kept pace. Without clear accountability, robust controls and well-defined operating models, production deployment becomes significantly harder.
That is why AI sovereignty is not just about infrastructure. It also depends on governance, security and assurance being built into the delivery process from the outset. This is particularly important in government, defence, law enforcement and other regulated sectors, where trust, compliance and resilience are non-negotiable.
How to put AI sovereignty into practice
It starts by identifying which data, services and capabilities must remain under your control. From there, technology choices should support interoperability, portability and long-term flexibility rather than creating new dependencies.
Open standards, modular architectures and cloud-agnostic deployment approaches all contribute to that outcome. Just as importantly, governance should be embedded from day one, with appropriate security controls, model oversight, auditability and clear accountability built into the operating model rather than added later.
Designing for AI sovereignty with CACI
The organisations making the greatest progress are not choosing between innovation and control. They are designing for both.
That is where CACI brings practical experience. Working across secure cloud, data platforms, digital identity and AI-enabled transformation, customers can build environments that are resilient, interoperable and governed from the start with our support.
As these conversations mature, sovereign cloud capabilities are becoming an increasingly important part of the wider strategy. CACI’s role as an AWS European Sovereign Cloud (ESC) launch partner reflects our commitment to helping customers adopt AI and cloud services while maintaining greater control over critical workloads, data and compliance requirements.
AI sovereignty should not be seen as a barrier to innovation. When organisations build control, governance and interoperability into their platforms from the outset, they are in a much stronger position to confidently adopt new technologies and adapt as the landscape continues to evolve.
AI in production: Why foundations start with outcomes
Jonathan Ede
AI adoption is now widespread across most enterprises, but meaningful, scaled impact remains relatively rare.
Across finance, marketing, operations and technology teams, organisations are using AI to improve forecasting, automate processes, accelerate content creation and support decision-making. Yet despite this momentum, many still struggle to move beyond isolated successes and deliver consistent value across the business.
The challenge is rarely the technology itself. More often, organisations rush to pilot tools and models before defining the outcome they are trying to achieve. In many cases, they also make assumptions about what their foundations should look like, centralising data, building platforms or designing architectures before they fully understand the problem they are trying to solve. The most effective foundations are rarely fixed; they emerge from a clear understanding of the outcome being pursued.
This matters because AI is not a single capability. Different approaches solve different problems, introduce different risks and place different demands on data, governance and operating models. The foundations needed for a predictive model are not the same as those required for a generative assistant or an agentic system capable of taking action across multiple platforms.
Trust sits at the centre of all of this. AI only delivers value when people trust the outputs, understand how decisions are being made and have confidence in the data, governance and security that sit behind them. The organisations seeing the greatest success start with the outcome, choose the right approach and build the foundations to support it. This article explores what those foundations look like in practice.
Choosing the right AI approach for your outcome
AI is often spoken about as though it is a single capability. In reality, it is a collection of different techniques, each designed to solve different problems and deliver different outcomes.
The organisations seeing the most success with AI don’t start by choosing a model. They start by defining the outcome they want to achieve, then selecting the approach best suited to delivering it.
While there are many different flavours of AI, the three below represent some of the most common approaches used in organisations today. For a deeper dive into the wider AI landscape and real-world use cases, see our AI Playbook, written by CACI’s Director of Data & AI Ethics, Sue MacLure.
AI approach
What it does
Example business outcomes
Foundation requirements
Key governance & control considerations
Predictive AI
Uses historical data to forecast future outcomes.
Predicting customer churn, forecasting demand or identifying risk.
Consistent, high-quality historical data with clear definitions and strong data quality controls.
Data quality, bias monitoring, explainability and auditability of decisions.
Generative AI
Creates new content or enables natural language interaction with information.
Well-structured, trusted information sources and effective grounding mechanisms to improve accuracy.
Output governance, hallucination management, security of sensitive information and responsible usage policies.
Agentic AI
Coordinates systems, data and tools to take actions on behalf of users.
Automating workflows, resolving customer requests or orchestrating business processes.
Reliable integrations, access to multiple systems and clearly defined operational boundaries.
Action authorisation, monitoring, human oversight, security controls and accountability for decisions.
These differences matter because each approach places different demands on the organisation.
A predictive model built on poor-quality data will produce unreliable forecasts. A generative AI assistant without access to trusted information may produce convincing but inaccurate responses. An agentic system operating without appropriate controls can take actions that create operational or security risks.
The organisations that scale AI successfully recognise these differences early. They don’t apply a single blueprint. Instead, they choose the right approach for the outcome they want to achieve and design the foundations, governance and operating model around it.
Designing the right data foundations for AI
There is no single blueprint for preparing data for AI. The way data should be structured, accessed and managed depends on both the outcome you are trying to achieve and the characteristics of the data itself.
Some information lends itself to centralisation and reuse. Other data is more valuable when it remains close to the source. Understanding the difference is key to designing data foundations that support AI effectively.
Data architecture is not one-size-fits-all
One of the biggest misconceptions in AI is that there is a single set of foundations that every organisation should build towards. In reality, the right data architecture depends on what you are trying to achieve. The outcome should shape the foundation, not the other way around.
Some benefit from being highly structured, unified and optimised for reuse. Others rely on data that changes too frequently or is too complex to move and store efficiently in one place.
In these cases, the focus should not be on centralising data, but on enabling secure, governed access to it where it already exists.
Designing your data architecture becomes a set of deliberate choices:
What outcomes are you trying to deliver?
Which data is critical to achieving them?
What needs to be standardised and shared?
What is best accessed directly from source systems?
How will models interact with that data in a secure and controlled way?
Designing for different data behaviours
The way data behaves should directly influence how it is structured and accessed. If, for example, a customer uses an airline’s AI assistant to ask about an existing booking, the underlying data is relatively stable. It can be standardised, catalogued and surfaced through a semantic layer, allowing the model to respond quickly, accurately and at low cost.
However, if that same customer asks, “How much will it cost to fly to Lagos next week?”, the answer depends on constantly changing inputs such as pricing, availability and demand.
In this case, centralising the data provides little value. Attempting to store and cache it introduces complexity and risk without improving accuracy. Instead, the priority shifts to enabling secure, real-time access to source systems, with the appropriate controls in place to ensure data is used safely and correctly.
Trust, governance and control are architectural decisions
What was once used by a small number of specialists becomes available to many users and systems, often at much higher speed and frequency. Without the right controls, this can quickly expose issues that were previously hidden.
For example, teams working closely with data often build informal safeguards, manually correcting inaccuracies or filtering out known issues. When AI automates those processes, those safeguards disappear. The same data is now consumed at scale, increasing the risk of errors, bias or misuse.
This is where governance becomes critical.
Data needs to be:
catalogued, so it can be found and understood
labelled, so its meaning, sensitivity and usage are clear
traceable, so it is possible to see where it came from and how it has changed
controlled, so access is appropriate and auditable
Without this, AI systems cannot be trusted, regardless of how well the model performs. Read more in our insight report on how clean data enables good AI.
Creating a shared understanding of “truth”
When multiple teams and systems rely on the same data, consistency becomes critical.
A “customer” in marketing may not mean the same thing in finance. Without clear definitions, models will produce inconsistent outputs, undermining trust and making results difficult to act on. Approaches such as semantic layers and structured data models help address this by creating a shared, governed view of key data assets, while still allowing for context where needed.
The goal is not to unify everything. That is slow, costly and rarely achievable.
Instead, it is about:
identifying high-value data
creating clear definitions and ownership
and enabling access through well-governed integration
People and operating model
As AI takes on more of the execution, roles shift from doing the work to directing it, interpreting outputs and taking accountability for decisions. AI removes tasks, but not responsibility.
This creates a fundamental change in how organisations need to operate. Teams are no longer just delivering outputs, they are working alongside systems that generate, recommend or take action on their behalf. That requires new skills, clearer ownership and different forms of oversight, with the level of control depending on the type of AI being used and the outcomes it is supporting.
Trust is what enables adoption
For AI to be used at scale, people need to trust it. That trust is not created through mandates or targets. It comes from confidence that the system is:
using the right data
producing reliable outputs
operating within clear boundaries
Without that, adoption will always be limited. People will either avoid using AI altogether, or use it cautiously and inconsistently, which limits its impact.
This is where governance and transparency play a critical role. When people can understand how a system works, where its data comes from and how decisions are made, they are far more likely to engage with it confidently.
Ways of working must evolve
One of the most common failure points in AI adoption is that organisations introduce new technology, but keep existing ways of working.
AI works best in environments where:
teams are cross-functional
data, technology and business functions collaborate closely
accountability for outcomes is clearly defined
Without this, AI remains isolated in pockets of the organisation rather than becoming part of how it operates day to day.
This often requires structural change. Not necessarily to reduce headcount, but to align skills and roles to where value is created. In many cases, it is about redeploying people, not replacing them.
This is a shift, not an optimisation
AI can deliver immediate value by helping organisations do things faster. But the longer-term opportunity lies in reimagining how work is designed, delivered and experienced.
When Thomas Edison invented the lightbulb in 1879, candlemakers didn’t look for ways to use it to produce candles more efficiently. They recognised that it required a fundamental shift in how light was created and used.
The same applies to AI. If organisations focus only on optimising existing processes, they will limit its potential. The real opportunity comes from stepping back and asking what work should look like when AI is part of the system.
With only 12% of organisations feeling prepared to adopt AI in day-to-day operations, it’s clear that very few have fully figured it out. As AI continues to evolve at pace, so too do the ways it can be applied. But those that are already thinking in this way, starting with the opportunity rather than the constraint, are the ones best positioned to move beyond incremental gains and realise meaningful, scaled impact.
Ultimately, AI only delivers value when it is embedded into how the organisation operates. That requires people to trust it, understand it and have clear accountability for how it is used.
AI success looks different across the organisation
Different parts of the business will define AI success differently.
For technology leaders, success often looks like scalable, secure systems that can be trusted to run reliably. For finance teams, it is about cost control, efficiency and measurable return. Data leaders focus on quality, governance and ensuring outputs can be relied upon. Marketing teams may look to AI to personalise experiences, reach the right audiences and improve campaign performance (for more on how AI can help you achieve this, see our whitepaper on AI decisioning).
A marketing team cannot deliver effective personalisation without access to well-structured, trusted data. Finance cannot measure ROI without visibility into how models are performing and what they are costing to run. Technology teams cannot scale AI safely without strong governance, security and integration in place.
This is where organisations often get stuck. AI initiatives are prioritised within individual functions, but the underlying foundations are shared. When those foundations are weak or inconsistent, every use case is affected, regardless of where it sits in the business.
The organisations that succeed recognise this early. They align around common foundations, even as teams pursue different outcomes. In doing so, they create an environment where AI can be applied consistently, safely and at scale.
Turning AI into something your business can rely on
Getting AI into production is not a technical milestone. It is an organisational one.
The challenge is rarely a lack of capability. It is knowing how to apply that capability in a way that aligns with business outcomes, works within real-world constraints and can be trusted at scale.
This is where the difference between experimentation and impact becomes clear. Successful organisations do not treat AI as a bolt-on capability. They design it into how their data is structured, how their systems operate and how their people work.
At CACI, this is the approach we bring to AI. Built on decades of data expertise, we combine deep technical specialism with a practical understanding of how businesses operate. That means going beyond models and tools, taking the time to understand the outcomes you are trying to achieve and designing the architecture, governance and operating model to support them.
Crucially, this is done with trust at the centre. AI only delivers value when people understand it, adopt it and have confidence in how it is being used. That requires strong data foundations, clear governance and a human-centred approach to how systems are designed and deployed.
Because ultimately, successful AI is not about implementing technology. It is about embedding it in a way that works for your people, your processes and your long-term goals. To learn more about how CACI can help your organisation architect AI for scale, get in touch to start the conversation.
Rethinking “buy, not build” in the age of Agentic AI
Mark Murphy
How agentic AI is redrawing one of tech’s most enduring rules of thumb
Agentic AI is beginning to change how software is developed, particularly in how quickly teams can generate and iterate on code. While this has clear implications for cost and speed, it does not remove many of the underlying complexities of software delivery, and in some cases introduces new ones.
For decades, organisations defaulted to “buy, not build” because building was costly and slow, while off-the-shelf software became more mature, reliable and easier to adopt. That balance is now beginning to shift. Agentic AI is making it faster and, in some cases, more cost-effective to create bespoke solutions, starting to change the economics of building software.
However, adopting AI at scale is proving more complex than the technology itself. Many organisations are experimenting with AI-assisted development, but scaling it remains challenging due to skills gaps, governance requirements, trust and integration into existing engineering practices.
The Buy vs Build reality is more nuanced: while AI can accelerate parts of development, it has not replaced the need for strong operating models, domain expertise or human oversight. The advantage comes from combining AI speed with human expertise, not replacing one with the other, a theme explored further in our AI playbook.
Why “buy” won
To understand whether the Buy vs Build rule is changing, you first have to understand why it arose. The instinct is often to frame it as a cost argument: developer time is expensive, so buying a ready-made product is cheaper. That is true, but it undersells the real reasons.
Developer scarcity drove up opportunity cost
Every engineer hour carried an opportunity cost. Building internal tools meant not building something else. The constraint wasn’t just capacity, but trade-offs: investing in non-differentiating systems often came at the expense of innovation or competitive advantage. “Build versus buy” was really a question of value.
Mature products embedded decades of domain knowledge
A well-established CRM (Customer Relationship Management), ERP (Enterprise Resource Platform) or risk platform is not just software. It is the accumulated wisdom of thousands of client implementations, regulatory cycles, edge cases and hard lessons. In these cases, the code mattered much less than the years of accumulated wisdom built into the product.
Operational burden was real
Before cloud-native infrastructure matured, owning a codebase meant owning a significant operational liability alongside it.
Requirements compromise was an acceptable trade-off
Bending processes to fit the software was not ideal, but often a reasonable trade-off because the alternative was too costly.
The result was “buy” becoming the default and “build” only winning when the capability in question was genuinely core to competitive differentiation, and even then, only if the organisation had the engineering depth to sustain it.
Crucially, “buy” never had to justify itself. It was the default. The burden of proof sat entirely with anyone proposing to build, much like the dynamic seen with “cloud-first” strategies, where cloud deployments sailed through architectural governance unchallenged, and it was only on-premise proposals that faced scrutiny.
What Agentic AI changes
Agentic AI – the class of systems that can plan, write code, test it and iterate with increasing levels of automation – directly affects the most visible cost in the build equation: the writing of the code itself.
As tooling matures and agents become more capable of managing their own context and quality gates it shifts the role of engineers from pure builders to orchestrators of AI-driven development.
This shift does not simplify the role of engineering teams, it expands it.
Engineers are increasingly required to work across architecture, governance, security and compliance, often in closer collaboration with legal, risk and business teams.
But what are the consequences for engineering leaders?
Greenfield bespoke tooling becomes economically viable again
Internal tools, data pipelines, workflow automation, custom reporting layers, the kind of work that reliably lost the buy-versus-build analysis on cost grounds for the past fifteen years, can now tip the other way, becoming economically attractive for organisations that previously lacked the scale, budget or technical capacity to justify building in-house.
However, this shift should not be mistaken for simplicity. Much of the cost and complexity of software delivery has never sat purely in writing code. Activities such as requirements gathering, low-level design, security and compliance, efficiency, integration with existing systems, deployment, user adoption and change management remain significant and often more challenging than the development itself.
This is particularly true in existing enterprise environments, where systems are designed for interoperability, resilience and regulatory compliance. While AI makes it quicker to purely generate code, it does not shortcut the design, architecture and contextual elements that has always made software development challenging and exacting.
The cost of requirement compromise falls
Buying off-the-shelf software always meant accepting a trade-off: your processes bent to the software’s logic, not the other way around. Agentic AI changes that calculus. When you can build to your exact requirements at a fraction of the previous cost, that compromise becomes much harder to justify.
Iteration replaces specification
AI-assisted development changes the nature of the build process itself. You no longer need a complete, validated specification before you start. You build, observe and refine cycles that were previously too expensive except for the highest-priority systems.
Why “buy” does not collapse
Despite these shifts, it is important to recognise that many of the original reasons for buying software remain unchanged.
The case for buying has been challenged, but the need has not disappeared. The strongest arguments for buying were never really about code in the first place.
Compliance and security hardening cannot be generated
A mature SaaS product carries years of penetration testing, third-party audits, SOC 2 certifications, GDPR machinery and incident response history. An AI agent can generate code; it cannot generate the audit trail, vendor liability or the enterprise trust that took years to earn.
Ecosystem and integration value is sticky
Established platforms and ecosystems remain the logical choice to “buy” because everything else connects to them. That network effect does not erode simply because building has become cheaper.
Deep domain knowledge still requires human time to reconstruct
Think of a credit risk engine, a tax calculation platform or a clinical trial management system. The rules encoded in that software represent decades of regulatory interpretation, institutional learning and hard-won edge-case handling. A prompt alone does not reconstruct that and attempting to do so carries real risk.
AI-generated code requires stronger human oversight, not less
AI can accelerate development, but it does not replace the need for engineering judgement. Someone still needs to define the architecture, set quality standards, manage dependencies and make the call when AI generates something that looks right, but is not.
What changes is the nature of the role. Engineering teams shift from writing every line of code to directing, validating and governing AI-generated output. That requires new disciplines: clearer architectural guardrails, stronger review practices and teams trained to work effectively with AI systems.
Organisations that treat AI as a shortcut around engineering rigour will see the cost return quickly, in the form of rework, security gaps or fragile systems. The advantage comes from combining AI speed with human oversight, not replacing one with the other.
The “buy” vendors are using the same tools
The gap does not close only from the build side. SaaS providers are accelerating their own development with exactly the same AI capabilities. The competitive starting point keeps moving.
The result is not a reversal of the buy-versus-build dynamic, but a more nuanced version of it.
The old mantra was binary. The new reality is a spectrum, and a better way to frame it is:
Build what differentiates you. Buy the commodity. The principle remains, but agentic AI has moved the boundary. Understanding what to build, buy and how to do both in a scalable, secure way is where the real challenge exists. Many organisations are not yet equipped to make those decisions confidently.
Previously, “what differentiates you” was a very narrow slice. The cost of building meant only truly proprietary capabilities, core algorithms or unique models, could justify investment, with everything else treated as commodity.
Agentic AI expands that slice. Capabilities that were previously too costly to build, such as internal tooling, data pipelines or workflow automation, are now worth revisiting.
However, the “always buy” category remains where value is not in the code itself: regulated platforms, established ecosystems and software underpinned by deep, embedded domain knowledge that is costly and risky to replicate.
The nuance worth preserving
It would be a mistake to read this as a simple reversal, “build, not buy” for a new era. The discipline behind the old mantra still matters and some of it deserves to survive. The question remains “Why does this need to be bespoke?” The answer just has a lower bar to clear than it did before.
The mantra is not dead; it’s being renegotiated.
Of course, it would be a mistake to think of this as a binary option. Agentic AI development is blurring the lines as to what Buy really means, and what Build is in practice. Increasingly, organisations are less concerned with whether something is “built” or “bought”, and more focused on delivering outcomes.
In practice, this means combining AI-generated code, cloud-native resources, third-party platforms and internal components to achieve the desired result, rather than treating build and buy as separate decisions. Blending components and capabilities into a single platform.
The middle ground
There is still a demonstrable need to utilise buy components within a “build first” environment, especially where there are specific requirements and needs around security, governance, perform, context and compliance.
However, there is also a growing middle ground, where organisations combine custom development with proven accelerators and platforms. These approaches retain flexibility while reducing risk, particularly in regulated or complex environments.
For example, accelerators such as CACI’s Jezero enable organisations to accelerate delivery while embedding proven patterns around security, governance and architecture.
This allows teams to take advantage of AI-assisted development without starting from scratch or introducing unnecessary risk.
How organisations should respond safely and effectively
Reopen “build versus buy” decision-making: The economics have changed, meaning areas that were previously considered a commodity should be reassessed.
Establish governance for AI-generated code: Define quality gates, dependency policies or any architectural guardrails.
Design an AI-ready operating model: AI-assisted building is risky without the right operating model and teams skilled in directing and governing AI outputs in place.
Partner with a trusted specialist: Most organisations lack the governance, architecture and compliance frameworks to scale AI effectively, which is where a trusted partner can make all the difference.
Agentic AI is quickly becoming part of the standard development toolkit. While it creates clear efficiencies, it also demands stronger governance, critical thinking and well-defined guardrails to ensure systems remain secure, maintainable and fit for purpose.
At CACI, we’ve approached this shift with a focus on control as much as capability. We have embedded defined patterns, development standards and governance controls into how AI-assisted development is used, ensuring that code generated through these approaches aligns with security, architectural and operational requirements from the outset.
Understand what to build, what to buy and where Agentic AI creates real advantage
The build-versus-buy boundary is shifting, but changing that boundary without the right controls introduces as much risk as opportunity.
Agentic AI can reduce the cost of building. It does not reduce the consequences of building the wrong thing, in the wrong place, without the right governance. Navigating this shift requires more than new tools, it requires critical thinking, strong architecture, and deep technical and domain expertise.
At CACI, we help organisations re-evaluate build-versus-buy decisions in light of Agentic AI, not just from a development perspective, but across operating models, governance and long-term ownership. That means understanding where AI genuinely changes the economics of building, how to integrate it effectively into software engineering processes, and where proven accelerators can de-risk and accelerate delivery.
For organisations looking to explore these challenges in more detail, we’ve also captured insights from our recent Architecting the AI-ready enterprise breakfast briefing, to provide a practical view of what adoption looks like in reality.
Ultimately, this is about combining the best of both approaches, AI-assisted development, established platforms and learned experience of complex environments, to build differentiated capabilities in a way that is scalable, secure and sustainable.
This is not about building more; it’s about building where it matters, and knowing where it does not. If you are reassessing how Agentic AI should shape your technology strategy, speak to our specialists to explore how to move forward with clarity and control.
How to use customer insights to improve QSR loyalty programmes
From increased competition to navigating social media trends, understanding customers is essential to QSR loyalty programmes.
With ever-increasing competition in the QSR (quick service restaurant) space, brands are increasingly focusing on customer loyalty to maintain and grow market share. Of course, brand loyalty is nothing new across the retail sector, but there are myriad ways of achieving it in today’s increasingly convenience-led environment. From reward schemes and direct customer engagement to novel menu items and canny social media campaigns and advertising, loyalty programmes are competing on multiple fronts to capture customer loyalty. The customer experience is essential to this, with fast food operators honing in on customer insights to deliver positive experiences to drive repeat visits.
This goes beyond just understanding what their favourite order is. Do you know who they are? Factors such as gender, age, employment and affluence inform trends such as which type of restaurant they are most likely to frequent. Do you know where they are? Understanding where they live, work and socialise, then where they are in the digital world in terms of social media platforms and apps they use. Then, crucially, do loyalty programmes know how to target them? It’s one thing gaining customer insights, another thing acting upon them effectively.
Loyalty, in an increasingly congested market with new entrants competing for the same customer base, has never been more important to operators. Here, we’ll take a closer look at achieving customer insights and effectively acting upon them to build brand loyalty.
Identify your customer
Understanding the demographic data around a brand is the first step to achieving this. By diving into granular local data, it is possible to identify who lives there and who they are. This covers their profile across gender, age, affluence, spending habits, digital trends and overarching lifestyle habits. Are they likely to visit and/or order from a fast food restaurant? If so, which type and how frequently?
In urban areas, the local demographic can change rapidly, meaning that it’s important to regularly monitor what’s happening around a QSR and be agile to any changes. What works today won’t necessarily be best tomorrow. This is why understanding customers is so crucial for loyalty programmes.
Identifying customers helps brands to build up a knowledge base that will inform their loyalty programmes. With so many marketing channels available, knowing your customer is paramount to effectively targeting them. It pays to know your customer and take advantage of marketing routes that offer them a bespoke experience.
CACI provides demographic data across the UK to a multitude of organisations. You can read about our work with organisations, like Chopstix. They all need to understand the same thing: who lives near their services and who would benefit from them. By being able to identify customers around their sites, operators can begin to strategically plan loyalty programmes based on tangible local insights, not just overarching industry trends. By having such insights, loyalty programmes can differentiate themselves from their competitors by providing more targeted and bespoke experiences to customers.
Know where to find them
Brands need to know where their customers are in-person and digitally. Where do they live and work? What websites, social media and apps do they use? Combining such data with the knowledge of who they are, the personal insights become far more tangible and can be utilised to effectively target customers.
This falls under missions, the reasons why customers visit restaurants, and meeting them where they are, at the right moment, via the right marketing channels. For example, a customer is probably unlikely to order fried chicken in the morning, but they might be tempted outside of their usual dining routine at the end of a night out. The right messaging, at the right time, can be hugely effective to influence this decision.
This can be built upon using existing data from across a QSR’s customer base. If, for example, you have an app through which customers order, sending notifications at the right time helps, as does sending offers to customers who haven’t ordered in a while. This helps with the overarching customer experience and can be further built upon with seamless ordering, convenience and rewards.
How can operators energise and excite customers? Reaching customers where they are is integral to this, with bespoke social media campaigns, games, promotions and in-app experiences essential to this process. If customers feel excited by a brand, this is a major step towards building brand equity and loyalty in their eyes.
A real-world example of this is the work with Domino’s. CACI’s expertise in customer experience and transformation supported Domino’s to effectively target customers with the appropriate pizzas and offers, crucially delivered at the right time. While Domino’s defined and created the offers themselves, CACI enabled and supported the delivery of these offers to the right audiences. CACI also integrated demographic, wealth, and catchment data into its customised solutions, enabling Domino’s to understand who its customers were and how their locations related to their sites.
Understand how to target them
Knowing how to target customers is essential. You have the info, but what do you want and need to achieve from your loyalty programme? The industry has been awash with innovation. From in-store games to product placement deals with major film releases, to reward cards and loyalty apps, there are several routes to market and several media through which to activate them. It’s all about standing out in a crowded market by offering unique and captivating experiences that drive repeat engagement.
What works for one customer, however, won’t necessarily work for another. This is why it’s so important to gather relevant information on them, from who they are to where they are.
It’s also vital that QSRs carefully consider what the aims of any loyalty programme are. Running them can often be expensive. For example, if it’s decided that an app is the right way to go, then the build, innovation, cost and maintenance within that infrastructure needs to be carefully considered upfront.
Revisiting loyalty programmes frequently is equally important. In the food-to-go space, we generally see from our demographic data among Millennial and Gen Z customers that there is a desire for novelty. If your customer base widely consists of such customers, then partnerships, menu changes and competitions can be successful in building loyalty. For others, well-timed promotional offers and reward schemes may be more effective.
CACI works with several QSR brands to regularly review their loyalty programmes. We support them in understanding what is and isn’t working, whilst considering the bigger picture of what needs to be achieved within available budgets. Do you need an app? Strategic partnerships with influencers? Social media campaigns? Traditional media campaigns? Our data and expert team help brands to cut through the noise and make informed, strategic decisions based on desired outcomes.
Getting your QSR loyalty programme right
Loyalty isn’t a random reaction from customers it is a commercial imperative for operators in achieving long-term growth. Of course, there needs to be a baseline satisfaction with the delivery of product offerings and in-store locations and settings. If they don’t like the product, they’re unlikely to become repeat customers. Beyond that, however, there are myriad interaction points upon which brands can stand out from the crowd and offer unique experiences to customers.
Different brands are at different stages of this journey. For brands operating a limited number of sites , building an app and investing in multi-channel marketing activities isn’t viable. For multi-site and franchise brands, the situation is very different. It comes back to understanding who the customer is, where they are and how a restaurant can offer them an experience that retains them when they consider visiting a site in future.
Ultimately, it’s a case of activating the right insights in the right channels, at the right time. CACI’s data and expertise support loyalty programme wherever they are on the journey. Be that new entrant to the UK market interested in how your loyalty programme will succeed in a new market, revisiting a long-established loyalty programme or those looking at expanding or even starting out with a loyalty programme, we can help.
By equipping you with unparalleled consumer insights and consultancy on loyalty activation, we can support you in your loyalty programme, in standing out from the crowd and in establishing a programme that supports your business needs.
Discover more about driving customer loyalty in your business. Get in touch today.
Why disconnected CRM & data fragmentation limit personalisation
In the previous blogof this series, we explored the impact of website sprawl on an organisation and the hidden costs that arise as digital estates grow unstructured. In this next instalment, we dive into another major barrier: the limitations presented by disconnected CRM and digital platforms.
Many organisations are rich in customer data but operationally fragmented. Customer data ends up scattered across systems, teams and channels, creating the illusion of a connected customer view. Data in silos creates a false sense of maturity, a lack of understanding or coordinated action.
So, what common signs of CRM and data fragmentation limit personalisation the most and how can organisations safeguard their customer experiences?
Common signs of CRM & data fragmentation
Disconnected CRM or digital data often shows up when:
Customer data is disconnected from website behaviour
Campaign teams and customer teams use different definitions and audiences
Reporting across systems is inconsistent
Teams cannot activate segments consistently across web, email and paid media
While these signs may appear gradually, they can affect every part of the customer experience once they do.
Why this becomes a customer experience problem
Data silos do not just slow down reporting, but also create friction across entire customer journeys.
Disconnected data causes customers to receive duplicate or mistimed messages and personalisation feel superficial. Brands struggle to respond consistently across touchpoints and teams are unable to respond confidently without the full picture of the customer. Over time, trust and brand perception erodes and the ability to deliver connected experiences is compromised.
This is why we treat CRM and data integration as an ecosystem challenge, not a single-platform one. If platforms, data and experiences are not joined up, improvements in one area rarely translate into consistent customer outcomes.
What a more connected foundation enables
The formula to creating a truly connected customer experience is when CRM, digital behaviour, content and operational data work together rather than sitting in silos. CRM and data integration is not just a systems exercise, but the foundation to scalable personalisation, stronger decision-making and future-ready digital ecosystems.
When your data foundation becomes more connected, you will notice:
Consistent audience definitions and reporting across teams
Consent and preferences managed centrally and respected everywhere
Operations becoming increasingly efficient
Better collaboration across teams and channels
A stronger foundation in place for AI-enabled decisioning and personalisation.
Why joined-up systems are critical for ecosystem orchestration
Ecosystem orchestration is about more than just adding tools, but about joining up systems, platforms and data into one operating model. Integration is therefore not simply connecting systems point-to-point. It becomes invaluable when aligned with content and experience delivery, governance and journey design. When these work together, organisations can deliver the enhanced personalisation experiences they seek to.
How CACI can help connect your data & enhance personalisation
CACI’s approach to CRM and data integration is grounded in practical experience, helping organisations regain control and build a foundation for sustainable innovation.
Our experts can help you uncover how your digital estate is performing, identifying where your data flows—or does not—and how to speed up your insight-to-action journey to optimise your CRM.
The halo effect explained – and why it matters now
A consumer’s shopping experience is no longer a linear journey. They browse and research products online, visit physical stores, engage on social media and buy through a brand’s website and wholesale distributors. For landlords and retailers, this means that physical stores influence much more than just in-store sales.
This reality is what has made measuring the ‘halo effect’ critical. But what exactly is it and how can retailers and landlords leverage it to make better location-based decisions and monetise store performance?
Defining the retail halo effect
The ‘halo effect’ is the contribution a physical store makes to online sales in its surrounding catchment.
A physical store plays a crucial role in brand building. If a customer is frequently reminded of your brand by passing your store while on their commute, they will be more likely to purchase from your brand online. Offering a distinctive brand experience will not only enable your physical location to drive online sales, but ensure your shelved products stand out to customers already spoiled for choice.
Ultimately, a strong physical store presence will enhance digital performance.
Why the halo effect is critical for retailers and landlords
Whether you are a retailer aiming to understand the true value of your stores or a landlord looking to attract the right tenants for your centre, being able to clearly measure how each store presence drives online revenue leads to better decision-making. As consumer behaviours evolve, understanding and quantifying this relationship has become crucial.
Making sense of the halo effect in practice
Viewing all channels as interconnected is necessary in modern retailing. By measuring the halo effect, you can understand exactly how a physical store’s presence will impact digital performance and where potential opportunities lie.
For landlords
When a tenant’s stores drive strong online sales in the surrounding area, engaged and high-spending shoppers are easy to attract to the broader retail destination as a result. Quantifying this cross-channel synergy helps you:
Draw a more precise picture of total revenue and brand impact
Understand how your physical presence influences your online revenue
Recruit the right tenant mix
Set fair rent expectations
For retailers
As a retailer, understanding the online revenue tied to a physical location will show whether a store is pulling its weight. If a location seems to have low in-store sales but a robust online halo, closing it might mean losing profitable online business. Being equipped with halo effect insights affects everything from site selection and store relocations to lease renewals and marketing investments.
The strategic impact of the halo effect
Insights from a physical store are more than just in-store interactions. They generate brand exposure that leads to online sales, which is where measuring the halo can be particularly useful in unlocking true value.
Refined network strategies: Attributing online sales back to store catchments offers you insight into exactly which locations are high performing.
Targeted investment: Depending on where the halo effect is seemingly strongest, you may opt for upscaling, refurbishing or increasing marketing around certain locations.
Risk management: Understanding the real online revenue at stake prevents costly mistakes before closing or relocating a store and that resources are allocated to areas offering the greatest return on investment.
Refined customer strategy: The online halo alone does not tell you whom to target, but reveals where your physical presence yields the biggest impact on online sales. Combining halo measurement with in-depth customer segmentation broadens strategic possibilities.
How CACI helps you measure and monetise the halo effect
By understanding the halo effect, you can improve location-based decision-making and discover the full picture of your interconnected physical locations and digital channels.
CACI helps retailers and landlords bring this to life. Our deep experience in shopper behaviour, demographic profiling and location analytics helps you extract meaningful insights from your halo measurements.
Our market insights ensure landlords understand where their tenants’ customers originate, who shops at specific locations and how to attract similar shopper profiles to other areas to improve tenant mix and increase footfall.
By layering the halo effect with demographic data, retailers can better assess where expansion or downsizing aligns with their target consumers’ shopping habits. Marketing campaigns can be tailored to amplify engagement and conversions across channels.
From understanding consumer catchment through Retail Footprint to evaluating online sales contributions via Brand Dimensions you can redefine the future of omnichannel retail, reassess investments and granularly view your stores’ performance.
In our first blog of our ecosystem orchestration series, we explored why fragmented platforms may be holding your organisation back and how to navigate them through ecosystem orchestration. In this blog, we uncover the signs of website sprawl arising, how it may be affecting your organisation, the hidden costs of these signs and how consolidation can help mitigate them.
Website estates rarely sprawl and fragment overnight. The gradual accumulation of websites is often the result of growth through business acquisitions or new sites being launched for different departments, products, campaigns or geographical regions. Each new site introduces its own hosting, security requirements, content workflows and maintenance demands.
Over time, what may once have seemed like manageable expansion becomes a complex web of disconnected platforms, duplicated content, siloed data and rising operational overheads. The actual cost of fragmentation becomes more than technical, negatively affecting your team’s productivity and resulting in disjointed user journeys and a poor overall customer experience with limited ability to personalise and capitalise on AI.
When digital expansion happens without a clear long-term governance strategy, a plethora of disconnected sites and technologies that are both difficult and expensive to maintain arise alongside fragmented user journeys and an inconsistent user experience.
In most organisations, the website estate sits at the centre of the customer journey. When it becomes fragmented, the knock-on effects show up across the wider ecosystem, from how content is managed and how performance is measured to how CRM and customer data are used to enable personalisation.
So, what are the warning signs that organisations should be on the lookout for when it comes to website sprawl and how might consolidation be the solution to this?
Fragmentation warning signs
If these signs sound familiar, website sprawl may be taking effect:
Inconsistent brand experience
Users expect a seamless journey regardless of where and when they engage with your organisation. When different sites across your estate have different look-and-feels, inconsistent messaging or tone and navigation discrepancies, a lack of trust may arise and lead to reduced engagement.
Duplicated content and publishing effort
With every increase in the number of your websites, there is an increased likelihood of content duplication and discrepancies. This ultimately becomes harder to manage and makes the job of updating content across your sites a time-consuming minefield. Without strong governance or systems in place to manage this amount of content debt, conflicting and inaccurate information will continue to snowball and leave both your internal teams and users frustrated.
Greater risk of security and compliance breaches
The more fragmented the estate, the more security vulnerabilities and increased likelihood of a malicious cyber-attack that devastates your business. This is especially true when it comes to older or forgotten websites that may not be fully patched. Similarly, as regulations tighten on key experience requirements like accessibility and data protection, the risk multiplies. Unless you have the operational bandwidth to monitor and maintain all your websites, you are opening yourself up for sanctions and fines.
Rising maintenance costs
Each website introduces its own infrastructure requirements, costs and challenges. Managing the maintenance, hosting and support of multiple platforms is time consuming and leads to duplicated efforts.
Hard-to-govern CMS landscape
If websites are built on different technology platforms, the operational burden grows substantially. Overhead increases when it comes to maintaining and building those sites. Integrations become more difficult and content and design changes require your team to learn multiple tools, workflows and processes.
Poor data visibility
Not only does a fragmented estate complicate gaining a unified customer view, but it obfuscates your websites’ analytics performance. Potential earnings are at stake because of the inability to provide users with personalised experiences and your team the ability to identify trends or insights to optimise experiences.
These signs often indicate that your organisation needs a refreshed ecosystem orchestration and governance strategy to ensure that you can continue to scale and meet the ever-demanding needs of your users.
The hidden costs for your organisation
The hidden costs of a website sprawl creep up in various places within an organisation. The operational drag of publishing and maintenance overhead can be felt by teams, while users grapple with inconsistent journeys that impact conversion and trust. Governance risks from compliance failures to accessibility issues and security exposure can arise and data fragmentation across platforms leads to measurement inconsistency.
This cumulatively blocks personalisation, as relevant experiences cannot be scaled without a consistent foundation.
What “good” consolidation looks like
Consolidation is about more than just reducing the number of websites in your ecosystem. It is about creating a coherent, manageable and scalable environment for your business to thrive digitally. When executed correctly, consolidation will unite each part of a digital estate under one governance model, ensuring consistency with content and design management. Its reusable components and shared design system, supported by a clear website and brand architecture, amplify this union.
A composable headless CMS is central to this. It can create a single source of truth and eliminate one of the biggest causes of website sprawl: duplicate content across multiple systems. By centralising content and enabling its reuse across multiple websites, organisations can reduce reliance on fragmented legacy platforms. Separating content from presentation allows organisations to manage multiple sites from a single platform while delivering consistent user experiences across channels. This modular approach also enables legacy systems to be migrated gradually, which improves governance and reduces duplication.
A shared measurement framework with analytics and tagging offers team comparable data and a single source of truth to work from. With accessibility built in by default, digital experiences can be enhanced and scaled confidently.
Why consolidation is the entry point to orchestration
Website consolidation is often where fragmentation becomes most visible, but it is rarely just a website problem. True value comes when consolidation is approached as part of a wider ecosystem direction.
Consolidation matters beyond websites because it:
Reduces digital sprawl and the “surface area of complexity”
Improves operational efficiency across teams and workflows
Streamlines the connection between journeys, data, CRM and personalisation
Creates a stronger foundation for consistent experiences, connected data and future orchestration
Sets up a scalable foundation for the future of orchestration and AI-driven experiences
How CACI can help with your website & CMS consolidation
CACI’s approach to website sprawl and consolidation is grounded in practical experience, helping organisations regain control and build a foundation for sustainable innovation.
We start by understanding your current environment, mapping out where sprawl and hidden costs are lurking. We then work with you to design governance frameworks, implement visibility tools and optimise your workloads. You gain ongoing support, regular reviews and continuous optimisation to retain your focus on what matters most: delivering meaningful experiences and fostering innovation.
Speak to our specialists today to assess where sprawl is creating the greatest operational drag and where consolidation can help you unlock the most value.
Next in our series, we will explore another common blocker to orchestration: how disconnected CRM and digital platforms limit personalisation, create inconsistency and what organisations can do to overcome them.
The hidden cost of enterprise complexity: structural, not technical
Many organisations believe complexity is a technology problem. They invest in new platforms, modern architecture and advanced analytics to simplify systems, processes and decision-making. Instead, complexity rarely decreases; it shifts shape.
The true challenge is structural.
Enterprises evolve through layers of decisions: new systems, new processes and new organisational models. Over time, these layers accumulate without a shared understanding of how they connect.
The result is familiar to every technology leader:
Change initiatives collide with unseen dependencies
Teams optimise locally, which can cause global friction
Transformation slows despite the use of better tools.
Technology alone does not solve this problem. What organisations often lack is a clear, shared understanding of how they work: what their core capabilities are, how systems and processes depend on each other, and where change will have knock-on effects.
When structure becomes explicit and living, complexity becomes navigable.
Why “more data” is no longer the answer
For years, digital strategy focused on data accumulation: data lakes grew, analytics platforms multiplied and dashboards became central to decision-making.
Yet many CTOs and CIOs now experience a paradox: more data does not always produce clearer decisions.
This is because insight without context creates ambiguity. Data shows patterns, but it does not explain what they mean for how the organisation works or what should change next.
Meaning requires structure; the relationships between systems, processes, risks and strategic objectives.
The next phase of enterprise intelligence will not be driven by more data, but by connecting data to organisational context.
The question shifts from: “What does the data say” to “What does this mean for how our organisation works and what should we change?”
The next evolution of enterprise platforms is model-driven
Enterprise platforms have evolved in a clear progression:
Documentation tools captured structure
Analytics tools captured performance
Low-code tools accelerate execution.
Each solved a problem, although none solved alignment.
A new class of platforms is emerging: ones that begin with a shared organisational model and are a digital representation of how capabilities, processes and technologies connect.
When applications and workflows are generated from this model, organisations gain something new: change becomes intentional rather than reactive.
Model-driven platforms do not replace existing tools, rather, they provide the connective tissue that allows them to work together coherently.
The future: Model-driven platforms, with low-code at scale
Low-code platforms have transformed how organisations build software by reducing friction, empowering business users and accelerating innovation.
But speed alone does not solve complexity, and as low-code scales, organisations may discover a new challenge: solutions can be built faster than organisations can understand their impact.
Applications multiply, dependencies become opaque and governance becomes reactive.
The limitation is not in low-code itself, but the absence of a shared model of the enterprise from which applications are built.
The next generation of platforms will shift from building apps to generating them from an organisational understanding.
Instead of designing every application independently, organisations will define how their enterprise works and allow systems to emerge from that foundation.
This is not a rejection of low-code. On the contrary, organisations cannot do without it. But it needs to operate within a more strategic, model-driven framework that aligns applications to shared enterprise goals.
Why this matters for CTOs and CIOS
As organisations grow in complexity, the challenge for CTOs and CIOs is no longer just delivering systems quickly, but doing so in a way that remains understandable, governed and aligned over time.
For CTOs and CIOs, this means:
Understanding the impact of change before it is implemented
Maintaining governance without slowing delivery
Keeping strategy, architecture and execution aligned over time
Scaling low and no-code safely without architectural drift
If the constraints of traditional low-code platforms, overstretched IT teams or the risks of poorly governed business-led development are limiting your organisation’s progress, there is a more robust path forward.
CACI’s model-driven enterprise platform, Mood, creates a living, digital representation of your organisation, connecting strategy, operations, systems, data and governance into a single, contextual enterprise model. This model becomes the foundation for application development, not an afterthought.
Rather than building disconnected apps on fragmented data, you build directly from enterprise truth.
By modelling how your business actually works, you can visualise dependencies, simulate change before implementation and generate operational applications directly from the enterprise model itself. Strategy and execution remain aligned because they share the same semantic core.
The result is controlled agility:
Transformation delivered at pace
Governance built in by design
Full traceability from boardroom objective to system change
Sustainable low/no-code development without architectural compromise
This is not just application development. It is enterprise orchestration.
If your ambition is to move beyond patchwork automation toward a truly model-driven enterprise, CACI can help you build it.
Reach out to us for a free consultation on how a digital twin may help your organisation become more agile to change. For more on what a model-driven framework looks like in enterprises, get in touch here.
In our first blog of this service design series, we assessed the impact of service design on end-to-end performance and why it is critical for leaders to understand its intricacies. This blog looks at the key role that discovery plays in service design.
Many organisations have already invested in service design: running a discovery, mapping journeys and building personas, uncovering pain points and presenting the findings. Yet despite the effort, very little remains unchanged in the day‑to‑day reality of how a service works. If that sounds uncomfortably familiar, you are not alone. Many leaders find themselves in the same position: plenty of insight, but not enough impact.
While service discovery is invaluable, it does not fix broken services, reduce operational costs or improve customer experience on its own. Insight is only powerful when it leads to action. This is the moment where most organisations stall and where the real work of service design begins.
What discovery will help your organisation achieve
Discovery surfaces the truth about how your service performs today, exposing friction, inconsistencies and unnecessary complexity. It reveals gaps between what users expect and what your organisation delivers through tried‑and‑tested methods:
Journey mapping to highlight where user effort is wasted or where support breaks down.
Service blueprinting to show the operational, policy and system-level issues creating that friction.
While these methods create clarity, clarity alone does not deliver change. It must be translated into decisions, prioritisation and delivery execution. Insight becomes valuable only when it moves beyond documentation and into operational improvement.
The most common point of failure in service design and transformation is not generating insight, but implementing it. This implementation gap is well recognised across large‑scale public service and organisational change, where strong discovery, policy or design intent often fails to embed into day‑to‑day delivery.
Why organisations struggle to move forward
No clear ownership of delivery, leaving recommendations without accountable leaders to drive them
Insights disconnected from a funded roadmap, so promising ideas never become prioritised work
Lack of governance or performance mechanisms to sustain improvements once they move into live operations
Misaligned teams (digital, ops, policy, technology) working on different goals, timelines and incentives
Operational complexity and legacy constraints that make changes difficult to implement at scale
Technology limitations that block even simple service improvements.
None of this is a failure of service design, but a failure of translation, from insight into action, from concept into delivery, and from isolated improvements into sustained, measurable performance gains.
What successful service transformation looks like
The organisations that unlock real value from service design treat discovery as the start, not the end. To convert insight into measurable operational improvement, they establish:
Clear prioritisation
A defined delivery roadmap
Alignment between digital, operational and customer teams
Governance and ownership
Measurement frameworks
How CACI helps turn discovery insights into operational changes
When it comes to service design, many organisations see the fastest wins by starting small. CACI’s quick‑start service design sprints are intentionally lightweight, low‑risk and designed to show value within weeks, not months. These are focused, time‑boxed engagements that target a single service, customer journey or operational hotspot, giving you immediate clarity on where improvements will deliver the highest return.
Because each sprint blends user insight, operational analysis and pragmatic delivery planning, you get tangible outputs fast: a prioritised set of improvements, clear owners and actions your team can implement straight away to maximise impact.
Whether you need a Rapid Service Assessment, a Blueprint Sprint or an AI‑Readiness Review, these agile engagements allow you to test the value of service design, prove ROI early and build momentum without heavy internal lift or long procurement cycles.
It is the fastest, safest way to turn insight into operational improvement with CACI supporting you every step of the way.
Discovery is essential, but value is only realised when insight leads to action and when service design is connected to delivery, governance and operational realities. For organisations that have already invested in discovery but now need to turn recommendations into measurable outcomes, this is the moment to bridge the gap.
CACI can help your organisation move from insight to implementation and from implementation to impact, translating discovery into decisions, decisions into action and action into service performance.
The quick service restaurant (QSR) sector is entering 2026 at a pivotal moment. Consumer demand remains resilient, but the operating environment is more complex than at any point in the last decade. Inflationary pressures, labour shortages, evolving customer expectations and rapid technological change are forcing QSR leaders to make sharper, more evidence-based decisions.
While much has been written about emerging QSR trends, many articles stop short of answering the most important question: which trends will genuinely deliver sustainable growth, and which risk becoming costly distractions?
Globally, the QSR market continues to grow, but that growth is increasingly uneven. According to market analysis of the UK foodservice sector, total market value is forecast to exceed £85bn by 2026, with growth driven largely by QSR and delivery-led formats.
However, this growth masks significant pressure beneath the surface:
Labour and food inflation have increased operating costs by 20–30% since 2019, according to hospitality cost analysis and UK inflation data.
More than 50% of UK consumers report actively cutting back on discretionary spending, including eating out.
Against this backdrop, trends are not abstract ideas — they directly influence network planning, pricing strategy, menu development and customer experience. Brands that understand how these trends play out locally are far better positioned to protect margins and unlock sustainable growth.
Top 7 quick service restaurant trends for 2026
1. AI as a strategic engine, not just a technology layer
Artificial intelligence has moved well beyond experimentation in QSR. In 2026, AI is increasingly embedded across forecasting, pricing, labour scheduling and customer engagement.
Additional industry analysis highlights that AI-enabled forecasting can reduce food waste by up to 25%, improving both sustainability and margins.
However, the biggest gains come when AI is treated as a strategic capability, not a bolt-on. Without high-quality customer data, location insight and behavioural context, AI risks reinforcing inefficiencies rather than resolving them.
What leading QSRs are doing differently:
Rather than deploying AI in isolation, leading QSRs are focusing on strengthening the data foundations that sit behind it. This includes improving customer data quality, linking transactional and behavioural signals, and incorporating location-based context into forecasting models. As a result, AI is increasingly used to anticipate demand, optimise decision-making and reduce operational risk, rather than simply automate existing processes.
2. Drive-thru reinvention: speed, accuracy and experience
Despite the growth of delivery and mobile ordering, the drive-thru remains the backbone of the QSR model. Industry analysis consistently shows that drive-thru accounts for nearly 75% of QSR sales in mature markets.
Increased use of queue analytics to manage peak-time congestion
Crucially, hospitality research shows that order accuracy and perceived friendliness have a greater impact on repeat visits than speed alone, reinforcing the need for balanced optimisation.
What leading QSRs are doing differently:
Top-performing QSRs are moving away from uniform drive-thru solutions and instead optimising performance at a local level. By analysing demand patterns by site, time of day and customer mix, they are better able to balance speed, accuracy and service quality. This approach helps direct investment towards the locations and peak periods where improvements deliver the greatest return.
3. Omnichannel ordering and digital transformation (with loyalty at the core)
By 2026, omnichannel is no longer a differentiator — it is an expectation. Customers move seamlessly between apps, kiosks, drive-thru and delivery platforms.
Industry data highlights that:
Customers engaging across three or more channels are 2.5x more valuable than single-channel customers.
The challenge lies in orchestration. Fragmented systems and disconnected data undermine both margin and experience. Leading QSRs are investing in a single customer view, unifying transaction, behavioural and location data to understand which channels genuinely drive incremental value.
What leading QSRs are doing differently:
Rather than treating channels independently, leading QSRs are building a more integrated view of the customer journey. By connecting data across mobile, in-store, drive-thru and delivery platforms, they gain clearer visibility of true customer value and channel interaction. This enables more consistent experiences, better-targeted loyalty strategies and improved understanding of which channels drive incremental growth.
4. Value-driven strategies in a cost-conscious market
Value has re-emerged as one of the defining QSR trends of 2026. According to UK consumer research, more than half of consumers actively compare prices before choosing where to eat.
Additional findings show that:
Bundled meals increase average order value by 8–12%
Limited-time offers drive trial without permanently eroding price perception
The most effective value strategies are location-specific, using data to tailor pricing and promotions to local demographics, competition and demand patterns.
What leading QSRs are doing differently
Instead of relying on national price promotions, leading brands are taking a more nuanced approach to value. By analysing local demographics, competitive intensity and purchasing behaviour, they are tailoring offers and bundles to specific markets. This allows them to respond to price sensitivity where it exists, while avoiding unnecessary margin erosion in locations where demand is more resilient.
5. Sustainability and packaging innovation
Sustainability is now a baseline expectation rather than a differentiator. Research indicates that over 75% of consumers expect QSR packaging to be recyclable or compostable.
Industry data also shows:
Packaging redesigns can deliver 10–15% material cost savings
Food waste contributes 8–10% of global greenhouse gas emissions, increasing pressure on operators to reduce waste
What leading QSRs are doing differently:
Leading QSRs are embedding sustainability into operational decision-making rather than treating it as a standalone initiative. By monitoring waste, packaging usage and customer response at a granular level, they are able to test changes, measure outcomes and scale successful approaches. This data-led approach helps balance environmental goals with operational efficiency and cost control.
6. Health, wellness and radical transparency
Health-led eating continues to influence QSR menus. Consumer studies show that over 40% of UK consumers actively seek healthier options when eating out.
Protein-forward and plant-based items continue to outperform category averages, while demand for clear nutritional and allergen information grows.
What leading QSRs are doing differently:
Rather than expanding menus uniformly, leading operators are using customer insight to understand how demand for healthier options varies by location and occasion. This allows them to introduce targeted menu changes, refine portion sizes and improve transparency without adding unnecessary complexity. The result is a more relevant offer that reflects local preferences while maintaining operational simplicity.
7. Ghost kitchens and virtual brands: a more disciplined model
Ghost kitchens remain relevant, but success depends on precision. Market analysis shows that location selection and demand modelling are the biggest determinants of virtual brand success.
Virtual brands are increasingly used to:
Extend trade area coverage
Test new concepts with lower capital risk
Optimise delivery economics
What leading QSRs are doing differently:
Successful operators are taking a more analytical approach to virtual brands and ghost kitchens. By combining demand forecasting, delivery radius analysis and competitive mapping, they are identifying opportunities that complement existing estates rather than cannibalise them. This disciplined use of data reduces risk and improves the likelihood of sustainable performance.
How QSR leaders can act on 2026 trends today
Understanding trends is only half the challenge. The real differentiator is execution.
To translate 2026 trends into commercial advantage, QSR leaders should focus on five practical steps:
1. Prioritise trends by impact, not hype
Not every trend will matter equally to every brand. Use data to assess which initiatives will:
Drive incremental demand
Improve operational efficiency
Strengthen customer loyalty
2. Ground innovation in customer insight
Customer expectations vary significantly by location, demographic and occasion. Advanced segmentation and behavioural analysis help ensure investment aligns with real demand.
3. Use location intelligence to guide decisions
From drive-thru optimisation to ghost kitchens, place matters. Understanding trade areas, cannibalisation risk and local competition reduces costly mistakes.
4. Test, learn and scale
Pilot new formats, offers and technologies in controlled environments. Measure results rigorously before national rollout.
5. Build a strong data foundation
Unified, high-quality data underpins every successful trend — from AI to personalisation to sustainability.
Future outlook: what comes next?
Looking beyond 2026, the QSR sector will continue to converge with retail and digital commerce. Automation will increase, but human service will remain critical. Data will become more central — not just for optimisation, but for resilience.
The brands that outperform will be those that:
Invest in insight, not just infrastructure
Optimise locally, not just nationally
Align innovation with measurable commercial outcomes
In a volatile environment, clarity beats complexity — and data-led decision-making is the most reliable route to sustainable growth.
Frequently asked questions about QSR trends for 2026
What are the top quick service restaurant trends for 2026?
The top quick service restaurant trends for 2026 include AI-driven operations, drive-thru optimisation, omnichannel ordering, value-led pricing strategies, sustainability-focused packaging and data-driven personalisation. These trends reflect rising cost pressures, digital adoption and changing consumer expectations across the QSR sector.
How is AI being used in quick service restaurants?
AI is used in quick service restaurants to improve demand forecasting, labour scheduling, order accuracy and personalised marketing. By 2026, many QSRs use AI to reduce food waste, optimise staffing and deliver more relevant customer offers in real time.
Why is value such an important trend for QSRs in 2026?
Value is a key QSR trend in 2026 because consumers are more price-conscious due to ongoing cost-of-living pressures. Quick service restaurants are responding with targeted value meals, bundles and promotions that balance affordability with profitability.
Are ghost kitchens still relevant in 2026?
Yes, ghost kitchens are still relevant in 2026, but they are used more selectively. QSR brands now rely on demand modelling, delivery radius analysis and location intelligence to ensure ghost kitchens are commercially viable.
What role does data play in QSR trends for 2026?
Data plays a central role in QSR trends for 2026 by enabling better decision-making across pricing, site selection, customer engagement and operations. Brands that integrate customer, transaction and location data are better positioned to adapt to market changes.
How can quick service restaurants prepare for the future beyond 2026?
Quick service restaurants can prepare for the future by investing in strong data foundations, customer insight and flexible operating models. This allows QSRs to test new concepts, optimise locations and respond quickly to evolving consumer behaviour.
Share of Wallet: The definitive guide to customer growth
Customer acquisition costs continue to rise, and the dynamic is even more pronounced in financial services, where competition for deposits, primary current accounts, and long-term savings has intensified. Research from the Harvard Business Review shows that it can cost up to five times more to acquire a new customer than to retain an existing one. Meanwhile, customer expectations have increased, switching barriers have fallen, and digital competitors are often just a click away. Within financial services, Open Banking has further accelerated switching and multi-banking behaviour, giving customers more freedom to distribute their balances across multiple institutions
Organisations that focus only on acquisition risk spending heavily without ever realising sustainable growth. This is particularly true in financial services, where the cost of onboarding, KYC, AML checks, and compliance activities makes new customer acquisition especially expensive. As noted by Deloitte Insights, financial institutions that prioritise deepening existing customer relationships outperform those that rely heavily on acquisition-led strategies.
Through Share of Wallet, financial institutions can also:
Identify the value of balances customers hold elsewhere, giving institutions insight into hidden opportunities for deposit and investment growth.
Understand which demographics, products and regions are outperforming the base, simplifying the identification of priority growth segments.
Access aggregated SOW metrics and periodic reporting, enabling customer-level and portfolio-level performance tracking.
Track KPIs linked to long-term strategic initiatives, connecting balance growth with broader business outcomes.
Use granular data to inform personalised communications, targeting customers based on wealth indicators, behaviours and potential.
This guide explains what share of wallet means in a financial-services context, how to calculate it using balances and asset concentration, why it matters strategically, and the practical, analytics-driven methods institutions use to increase it. Drawing on use cases across banking, savings, credit, and wealth management — including work CACI delivers — this guide shows why leading FS organisations now treat balance-based SOW as a cornerstone of sustainable growth.
What is Share of Wallet?
Share of Wallet (SOW) in financial services refers to the proportion of a customer’s total account balances or savings “wallet” that they hold with your institution across products such as current accounts, savings, ISAs, investments, mortgages or personal loans.
For example, if a customer has total liquid savings of £40,000 and holds £10,000 of those balances with your bank, your SOW is 25%.
This measurement applies across the sector: the percentage of a customer’s investable assets held with a wealth manager, the proportion of deposits concentrated with a building society, or the share of credit balances placed with one provider.
SOW provides a more complete understanding of customer value by:
• Revealing the total wealth picture, rather than only internal balances. • Highlighting how much money customers hold elsewhere, enabling accurate opportunity sizing. • Filling gaps in financial understanding that internal data alone cannot provide.
Share of Wallet vs Market Share
The two metrics assess very different dynamics:
• Market share measures your institution’s total balances or products across the market. • Share of wallet measures the proportion of each individual customer’s financial life that you hold.
A bank may have high market share yet a low share of wallet per customer — signalling weak relationship depth. Conversely, a smaller provider might have very high wallet share among a loyal customer base.
SOW also supports strategic decision-making by enabling:
Tracking of balance growth KPIs across segments and product lines.
Monitoring long-term performance such as deposit acquisition, wealth onboarding and cross-product engagement.
Identifying “headroom” — the additional balances customers are likely to hold elsewhere that could be captured.
How to calculate share of wallet
The Basic Formula
SOW (%) = (Balances held with your institution ÷ Customer’s total balances) × 100
Example: • Total savings: £60,000 • Balances with your bank: £15,000 • SOW = 25%
Data Sources for Calculation
Internal account and balance data
Open Banking and aggregation tools
Customer research panels
Predictive modelling and machine-learning estimation of held-away balances
A strong SOW calculation enables institutions to:
Combine customer-level balance estimates with postcode-level and product-level data for a 360° view of financial behaviour.
Use CACI Retail Finance Benchmarking to understand typical wallet sizes, competitor penetration and localised patterns.
Integrate wealth estimates into modelling, segmentation and pricing cohorts.
Common Challenges
Hidden balances not visible to individual providers
Volatile liquidity movements
Categorisation differences across product types
Life-stage and macroeconomic factors influencing wallet size
Why Share of Wallet Matters
Cost-Efficient Growth
Deepening customer relationships by capturing more of their financial life is significantly more cost-effective than acquiring new customers. Increasing balance concentration boosts revenue per customer while lowering cost-to-serve.
Customer Retention and Loyalty
Customers who place a higher proportion of their savings or investment assets with one institution demonstrate far stronger loyalty and lower churn.
Lifetime Value
As wallet share increases, so does Customer Lifetime Value (CLV). Customers with deeper financial relationships are more likely to take mortgages, lending products, savings accounts and wealth services.
Strategies to increase Share of Wallet
Segment Customers by Potential
Not all customers have the same growth potential. SOW helps identify:
High potential, low share customers with substantial held-away balances
CACI helps institutions uncover these opportunities using demographic, geographic and behavioural insight.
Cross-Selling and Upselling
Examples include:
Encouraging current-account-only customers to open savings products
Moving savers from low-yield accounts to higher-value fixed-term or investment products
Introducing ISA or wealth solutions to customers showing investment readiness
Next best product models identify optimal timing.
Loyalty, Rewards and Relationship Pricing
Mechanisms include:
Preferential rates for customers consolidating savings
Bundles linking savings, current accounts and credit
Incentives for salary mandates or account funding
Bundling and Value Propositions
Product bundles and integrated financial management tools increase stickiness by offering convenience, clarity and control.
Customer Experience
Ease, trust and service quality materially influence wallet share. Positive digital and branch experiences translate directly into balance consolidation.
Financial Services use case: Share of Wallet in banking
Customer-Level Coding
Banks assess the percentage of customer balances they hold to identify:
Customers with significant held-away funds
Investment assets managed by competitors
Opportunities to deepen primary relationships
Savings Behaviour and Headroom
Balance-based analysis distinguishes between:
Fixed savings
Variable savings
Investment holdings
Customers with large variable balances but low SOW offer clear growth potential.
Segmentation by Demographics
Older customers often consolidate more; younger customers diversify more widely. CACI’s Fresco segmentation adds further behavioural and life-stage context.
Monitoring and Tracking
Modern analytics track:
Balance concentration shifts
Flow of funds in and out of held-away accounts
Changes in product mix and adoption patterns
How Institutions Use SOW
Identify and quantify customer-level opportunities
Use CACI Retail Finance Benchmarking and location intelligence to find geographic hotspots
Target segments with low share but high growth capacity
Avoid unnecessary rate rises for customers already showing high SOW Provide frontline teams with estimated SOW indicators for personalised engagement
Sector perspectives beyond Financial Services
Retail and E-commerce
Supermarkets compete to become the primary shopper destination. Loyalty cards, personalised coupons, and basket-building promotions all increase wallet share. E-commerce platforms use recommendation engines and premium memberships to keep customers buying within their ecosystem.
Telecoms and Media
Quad-play packages dramatically increase wallet share by consolidating multiple services into one bill. Customers who bundle are less likely to switch because of the perceived inconvenience of managing multiple providers.
B2B and Professional Services
For B2B firms, wallet share often means expanding into adjacent service areas. A consultancy may start with strategy and then cross-sell into analytics, technology, or managed services. Increasing wallet share in B2B builds long-term, multi-service relationships that are resistant to competitor approaches.
Share of Wallet pitfalls and limitations
Financial services face additional challenges:
Over-marketing: too many rate-driven offers can reduce trust.
Cannibalisation: shifting balances between products may not increase total value.
Balance volatility: savings can move rapidly in response to macro-economic signals.
Privacy and regulation: strict rules govern the use of customer financial data.
Institutions should balance ambition with transparency and ethical standards.
Advanced Share of Wallet analytics: The CACI approach
Real differentiation comes from analytics:
Predictive modelling: estimating total wallet and held-away balances.
Uplift modelling: identifying which customers are likely to consolidate more funds.
Controlled experimentation: validating rate changes or marketing interventions.
Dashboards: tracking SOW in real time across segments and product lines.
CACI’s data science services help banks turn SOW from a descriptive measure into a predictive, prescriptive engine for long-term balance growth.
Share of Wallet implementation roadmap
Assess: measure baseline balance concentration.
Prioritise: identify customers with high potential and low current share.
Execute: deploy at the right moment with meaningful personalisation.
Measure: track responses, adjust propositions, and optimise.
Evolving Dynamics of Wallet Share
Wallet share in FS is evolving through:
AI-powered personal finance tools influencing balance allocation.
Open Banking transparency enabling better competitor comparison.
Cross-category mapping (e.g., savings vs investments).
ESG-driven decision-making shaping where customers place their assets.
Conclusion
Share of Wallet is more than a KPI — it is a growth framework grounded in balance concentration and trusted financial relationships. By accurately measuring and acting on SOW, institutions can increase profitability, reduce churn, and deepen their role in customers’ financial lives.
CACI’s expertise in data science, segmentation, and customer insight helps banks move from generic cross-sell to intelligent, targeted strategies that materially increase the proportion of savings, balances, and financial value customers hold with them.
Share of Wallet FAQs
1. What is share of wallet in banking?
Share of wallet in banking refers to the proportion of a customer’s total account balances or savings that they hold with a specific financial institution.
2. How do banks calculate share of wallet?
Banks calculate share of wallet by dividing the balances a customer holds with them by the customer’s estimated total savings or assets, including held-away funds.
3. Why is share of wallet important for financial institutions?
A higher share of wallet increases customer lifetime value, improves retention, and strengthens the institution’s role as the customer’s primary financial relationship.
4. What is a good share of wallet percentage for banks?
A strong share of wallet typically means holding the customer’s primary current account and a significant portion (often 50% or more) of their liquid savings.
5. How can banks increase share of wallet?
Banks increase share of wallet by offering competitive savings rates, personalised product recommendations, relationship-based incentives, and frictionless digital experiences that encourage customers to consolidate balances.
6. What are held-away balances in financial services?
Held-away balances are savings or investment funds that a customer holds with other institutions, which represent potential share of wallet growth opportunities.
7. What affects a customer’s share of wallet?
Factors include trust, interest rates, digital experience, financial goals, risk appetite, and the convenience of managing multiple financial products in one place.
8. How does share of wallet relate to customer loyalty?
Customers who allocate more of their balances to one institution typically show higher loyalty, lower churn, and longer relationship tenure.
9. What tools do banks use to measure share of wallet?
Banks use predictive modelling, Open Banking data, demographic profiling, and internal balance analytics to estimate total wallet size and identify held-away funds.
10. What is a share of wallet strategy in financial services?
A share of wallet strategy focuses on increasing the proportion of a customer’s total balances, deposits, or investable assets held with the institution through targeted engagement and personalised offers.
Share of Wallet Analysis: How to measure and unlock customer growth
Most financial institutions recognise that retaining customers is more cost-effective than acquiring new ones. Yet few have a reliable method for understanding how much of a customer’s total savings, deposits or investment balances they actually hold, or how much value sits hidden in other institutions. This is where Share of Wallet Analysis becomes indispensable.
In financial services, Share of Wallet (SOW) reflects the proportion of a customer’s total financial holdings—savings, current account balances, fixed-term deposits, investments or unsecured lending—held with your institution. Share of wallet analysis refers to the methods, data and models used to measure, estimate and interpret a customer’s total balance wallet, including held-away funds. Done well, it uncovers hidden balance headroom, identifies consolidation opportunities, highlights attrition risk, and provides a roadmap for profitable balance growth.
In this article, we explore what share of wallet analysis means within financial services, how it is conducted, common analytical methods, and how advanced modelling transforms SOW from a static metric into a powerful engine for deposit growth, cross-sell, retention and customer value expansion.
👉 If you’re new to the concept of wallet share itself, start with our Definitive Guide to Share of Wallet for Financial Services and then return here for the measurement and analysis deep dive.
What is Share of Wallet analysis?
Share of Wallet Analysis in financial services is the process of calculating and interpreting the proportion of a customer’s total account balances held with your institution versus competitors. It goes beyond the raw SOW percentage to understand why customers distribute balances the way they do, what balance growth potential exists, where consolidation opportunities lie, and which customers present the strongest long-term value.
In practice, SOW analysis involves:
Measuring balances held with your institution
Estimating total customer wallet size, including held-away savings and investments
Identifying patterns across customer, product and demographic segments
Historically, banks and building societies often relied on surveys asking customers where else they held savings or investments.
Strengths:
Useful for capturing attitudinal data (trust, preference, propensity to consolidate)
Can identify perceived gaps in relationships
Weaknesses:
Self-reported balances are often inaccurate
Customers underreport or forget held-away accounts
Hard to scale reliably
📖 Research published in the Journal of Marketing Research shows that self-reported financial behaviour often underestimates total balances.
2. Internal Transactional and Balance Data
Banks, building societies and wealth managers hold accurate information about the customer’s primary account balances—current accounts, savings, term deposits, ISAs, loans and investments.
This is the foundation for customer-level SOW coding but requires external data or modelling to understand the full wallet.
3. Third-Party Panels and Benchmark Data
Industry benchmarks—such as regulatory publications, anonymised credit bureau data or aggregate financial panels—help institutions estimate likely total wallet sizes across segments.
Strengths:
Offers a market-level perspective
Useful for comparing your penetration against competitors
Weaknesses:
Panels may not align perfectly with your customer mix
Insights are directional, not customer-specific
A Deloitte report on financial services highlights that panel data supports competitive context but must be calibrated to segment differences.
4. Predictive Modelling
This is the most advanced and reliable approach for FS. Predictive models estimate total customer wallet size, including balances you cannot see, using behavioural indicators, demographics, product mix, income signals and external datasets.
Techniques include:
Regression models linking known balances to inferred total wealth
Machine learning models using hundreds of variables to predict wallet size
Uplift modelling to assess which actions drive incremental consolidation
Propensity-to-save and propensity-to-move models
At CACI, we combine internal balance data, segmentation, geography and market-level insight to produce a highly accurate picture of held-away balances, wallet potential and consolidation opportunity.
The process of Share of Wallet analysis
Step 1: Define the Financial Category
Define what counts as the “wallet”:
Liquid savings
Fixed-term deposits
Current account balances
Investment assets
Unsecured lending exposure
The category definition shapes both measurement and modelling.
Step 2: Collect and Integrate Data
Bring together:
Internal balance data
Product holdings
Customer demographics
External panels and benchmarks
Predictive model outputs
This is where CACI’s expertise in customer data integration and Retail Finance Benchmarking becomes essential.
Step 3: Calculate Current Wallet Share
Apply the adapted FS formula:
SOW (%) = (Balances held with you ÷ Estimated total customer wallet) × 100
Step 4: Segment and Prioritise
Segment customers into actionable groups:
High wallet, low share (big consolidation opportunity)
High wallet, high share (protect and retain)
Low wallet, high share (profitable but low headroom)
Low wallet, low share (limited upside)
Step 5: Apply Predictive Analytics
Model:
Total wallet value
Likely held-away balances
Customer headroom
Propensity to consolidate
Product-specific opportunities (savings, ISAs, term deposits, investments)
Step 6: Translate Insight into Action
Actions include:
Targeted savings growth campaigns
Relationship pricing for consolidation
Fixed-term renewal strategies
Investment readiness triggers
Personalised engagement sequences
Why advanced analytics makes the difference
Basic wallet share tells you the percentage you currently hold. Advanced analytics tell you how much you could hold, how to win it, and where the risks are.
Predictive Power
Models forecast wallet potential for each customer, identifying those most likely to consolidate balances.
Uplift Measurement
Uplift modelling isolates the true incremental effect of actions—ensuring incentives are only offered where they change behaviour.
Dashboards and Visualisation
Dynamic dashboards allow product, marketing and risk teams to track:
Wallet share
Flows in and out
Consolidation patterns
Segment-level performance
Forrester research highlights that organisations adopting advanced analytics see significant improvements in customer experience outcomes.
Sector examples of Share of Wallet analysis
Banking and Financial Services
Banks use SOW analysis to identify:
Customers with large savings held externally
Deposit consolidation opportunities
ISA or investment readiness
Mortgage customers without savings or wealth relationships
For example, a customer with high income and low internal savings may hold significant deposits elsewhere—representing high wallet headroom.
Retail and E-commerce (Contextual Comparison Only)
Retailers use similar principles, but FS analysis focuses on balances, not spend.
Telecoms and Media (Conceptual Parallel)
Bundling logic informs FS strategies such as linking current accounts, savings and credit.
B2B Services
Professional services firms use wallet analysis to expand into adjacent advisory domains.
Pitfalls in Share of Wallet analysis
Over-reliance on surveys
Poor data governance or misuse of Open Banking data
Treating all customers as having equal wallet potential
Short-term incentives that erode long-term margin
Misinterpreting volatility in savings (seasonality, life events)
Future of Share of Wallet analysis
The next decade will further accelerate SOW capability through:
AI-driven next-best-action models
Real-time balance monitoring through connected data ecosystems
Cross-category household finance modelling
ESG-aligned financial behaviour analysis
Organisations using AI-led wallet prediction will outperform those relying on historical balances alone.
Conclusion
Share of Wallet Analysis turns a simple metric into a strategic growth engine. In financial services, it reveals how much of a customer’s total savings, deposits and investments you truly hold, where your hidden opportunities lie, and what actions will maximise customer lifetime value.
By combining advanced analytics, data integration, segmentation and customer insight, financial institutions can unlock held-away balances, increase consolidation and strengthen their role in customers’ financial lives.
At CACI, we help institutions turn SOW analysis into measurable growth—building models, integrating data and designing targeted interventions that drive long-term, profitable balance expansion.
Low-code promises speed and greater autonomy for delivery teams. Done well, it can reduce bottlenecks and help organisations build and iterate quickly. But organisations that adopted low-code early are now finding that speed without shared structure can simply get you to the wrong place faster. The challenge is rarely the low-code tooling itself, but how it is used, governed and connected to the wider enterprise.
So, why does low-code hit a ceiling? What does that ceiling look like within organisations, and how can a meta-model remove it?
The unintended costs of using low-code tools
Low-code platforms are great for fast application development through drag-and-drop techniques, followed by adding the logic. This app-first approach can be fast and accessible, particularly for smaller teams and well-bounded use cases. However, at scale, the approach can come at a cost if there is no shared model to keep applications aligned and consistent.
Organisations may end up with a portfolio of disconnected, inconsistent and error-prone applications. Issues may go unnoticed, such as an increase in operational silos, technical debt and divergence from policy, but show up in:
Governance: “How many apps do we have?” and “What data do we hold?” Scalability: “We cannot reuse anything without breaking something.” Strategic: “We have automated today’s mess, not tomorrow’s organisation.”
The lack of structure around low-code is what causes these issues. Therefore, the aim should not be to automate fast, but to understand and evolve the organisation to deliver on its strategic and operational objectives coherently.
Low-code: Great for building applications, weak for structuring them
Low-code enables the speedy assembly of applications. However, as an organisation grows, complications arise. Without a clear structure in place, projects risk becoming scattered and hard to manage, and teams can struggle to reuse, govern and scale what they have built.
Before building any new application, assessing the organisation’s current situation and required changes is essential. Creating a meta-model that accurately reflects the organisation will offer a solid base for building applications, integrating new work, and maintaining consistency as delivery scales.
By beginning with the enterprise model, which defines organisational purpose, then mapping out semantic relationships for context, business logic becomes transparent. This approach enables genuine, evidence-based decision intelligence.
What is a meta-model?
A meta-model is a master blueprint of an enterprise. It captures the things that matter most about how the organisation works, and how those elements relate to one another, so that applications and workflows can be built with shared context rather than in isolation.
Using the analogy of a large housing development: although individual homes may vary in appearance and layout, they share common foundations, materials and construction processes to maintain consistent quality.
A meta-model does this for applications. It guides the creation of specific applications tailored to each use case by defining the structure and context, while upholding overarching standards.
It is the difference between a collection of diagrams and workflows and a living, navigable model of your enterprise that aligns to strategy.
Instead of thinking about building apps in isolation, the question becomes: “What organisational change are we enabling and how does it connect to everything else?”
Get the agility of low-code with the rigour of enterprise modelling
When low-code is underpinned by meta-modelling, everything changes:
Reusable, consistent and governed logical structure
Build interfaces that enable you to simulate and test changes safely
Align technical design with business strategy from day one
When enterprise structure becomes the foundation, speed and coherence stop being competing goals. They become complementary.
Platforms like Mood, CACI’s digital twin platform for actionable organisational transformation, combine no-code and low-code tooling with a powerful, flexible meta-model capability at its core. This means teams can keep the speed benefits of low-code, while gaining the shared context needed to scale safely and consistently.
What role do dashboards play?
Most organisations are rich in analytics. Dashboards track performance, visualise trends and surface insights faster than ever. Business intelligence has transformed how leaders see their organisations.
Yet many decision-makers experience familiar frustration: they can see the problem, but not the path forward.
Analytic platforms excel at answering:
What happened?
Where are trends emerging?
Which metrics changed?
But they rarely answer:
Which capability caused this?
What dependencies will be affected if we intervene?
How will change ripple through the organisation?
Understanding these questions requires more than data. It requires structure.
Enterprises are not just datasets. They are systems of interconnected capabilities, processes, technologies, risks and strategies. When this structural understanding is captured as a living model, analytics gains context. Instead of simply observing change, organisations can simulate it.
The future of enterprise decision-making lies not in more dashboards, but in connecting insight to organisational meaning and executing successful transformation.
The missing layer in digital transformation: Enterprise context
Many transformation initiatives struggle not because of lack of tools or investment, but because of fragmentation.
Different teams use different platforms:
Analytics tools for insight
Low-code tools for apps
Architecture tools for modelling
Project tools for execution
Each solves a piece of the puzzle, few connect them.
What is missing is a shared context, a way to understand how decisions in one domain affect another. Without this, organisations experience:
Duplicated solutions
Misaligned initiatives
Hidden dependencies
A model-driven approach introduces a new layer: a semantic representation of the enterprise.
This is not documentation for its own sake, but a living structure that connects strategy, operations, technology and execution. When applications, workflows and analytics align to this model, transformation becomes coordinated rather than fragmented, and agile to change rather than a rigid waterfall.
From documentation to execution: The evolution of enterprise architecture
Enterprise architecture has often been misunderstood as static documentation; diagrams that describe how systems are organised.
The role of architecture is changing, however. As organisations face increasing complexity, architecture is evolving from passive description into active orchestration.
The next generation of platforms does not simply document reality; it drives behaviour from it.
Model-driven approaches enable:
Applications generated from enterprise structure
Governance embedded into workflows
Decision impact analysed before implementation
Architecture becomes not a record of change, but the engine that enables it safely.
This shift represents a broader evolution: from understanding complexity to operationalising it.
The future enterprise platform: A digital twin for decision-making
The concept of a digital twin has moved beyond engineering into the organisational domain.
A digital twin of the enterprise is not merely a visualisation of assets or data. It is a dynamic representation of how an organisation functions; capturing relationships between capabilities, processes, systems and outcomes.
Such a platform allows leaders to:
Simulate change before execution
Understand cross-domain impact
Align strategy with operational reality
As AI and automation accelerate the pace of change, organisations will need more than tools that execute tasks quickly. They will need systems that understand context.
The future enterprise platform will not be defined by how many apps it builds or dashboards it produces, but by how effectively it helps organisations to understand themselves and evolve intentionally.
Don’t know where to start?
If the limitations of low-code, blockers by lack of IT resources or worries about the consequences of citizen development are impacting your organisation, CACI can help.
Reach out to us for a free consultation on how a digital twin may help your organisation become more agile to change.
How logistics organisations can safeguard against fuel volatility & rising prices
Fuel volatility has become one of the most significant challenges facing logistics leaders. The industry is highly susceptible to variability, and with ongoing disruption in global energy markets, rising fuel prices are driving up operating costs and putting wider network performance under strain.
Amidst the uncertainties, one thing is clear: logistics leaders must act now to prevent losses in their networks. So, what does this fuel volatility and rising uncertainty mean for the industry and how can leaders counter these effects?
What fuel volatility means for logistics operations
Three themes are emerging consistently across the sector.
Efficiency becomes non‑negotiable
Tiny inefficiencies scale fast across a fleet. What was once considered a “good enough” plan that worked at £x/litre often will not survive at £y/litre.
As fuel costs increase, efficiency is no longer a nice-to-have. Downstream, domestic fleets are particularly impacted, as higher fuel prices amplify the cost of everyday decision-making from route choice and stop density to vehicle utilisation and realistic drive times.
Cost forecasts must reflect real operations
Forecasting costs is more than just refreshing a spreadsheet. It is about grounding forecasts in what happens on the road, not what logistics leaders hope a plan will deliver.
While many cost models rely on planned mileage and theoretical routes, rising fuel prices expose a gap between what was planned and what happened, which becomes expensive quickly.
Re‑forecasting in this environment requires operational truth: understanding real mileage, real execution behaviour and where cost is genuinely being added, not assumed away.
Route compliance becomes the lever that matters most
Optimisation only creates value when executed. If the plan is not followed, you are not just missing savings, but layering on cost through extra miles, minutes and exceptions.
Route deviations, congestion and last‑minute re-planning add unplanned miles at much higher costs per mile. Extended upstream transit times increase pressure on domestic distribution to recover service levels, often at the expense of fuel efficiency. Fleet and light commercial vehicles have been swelling the electric vehicle (EV) market, so logistics organisations in a position to adopt electric vehicles (EV) into their fleet can further reduce their fuel dependency and cut costs.
How can logistics leaders counter the effects?
Logistics organisations that are coping best with fuel volatility are the ones treating efficiency as an ongoing operational discipline, not a one‑off optimisation exercise. Those prioritising the optimisation of their logistics operations via the most advanced algorithms and real-world data will stay afloat amidst uncertainty.
Planning optimal routes
When fuel prices rise, every unnecessary mile becomes a direct hit to margins. Organisations can counter this by using CACI’s advanced route optimisation to continuously minimise distance travelled, time on the road and fuel consumed – without compromising service levels.
By dynamically calculating the most efficient routes using advanced algorithms, organisations can reduce empty miles, avoid congestion and balance workloads more effectively across fleets.
Focusing on operationally realistic routes
Organisations that account for vehicle constraints, compliant roads and what drivers experience on the ground are creating the most operationally realistic routes and best placed to counter the effects of fuel volatility.
Closing the loop between planning & execution
Leaders shifting from planning quality alone to execution quality can:
Understand where and why deviations occur
Distinguish necessary exceptions from avoidable behaviour
Feed execution insight back into better planning
These help safeguard from fuel volatility and encourage efficiencies. By embedding efficiency as a discipline, grounding forecasts in operational reality and closing the gap between route planning and execution, organisations can move from reactive cost management to predictable and resilient logistics operations, even in uncertain conditions.
How CACI can help
CACI’s Logistics experts help organisations design efficient routes, re‑forecast costs using real operational data and ensure planned routes are executed. This ensures rising fuel costs do not automatically translate into rising inefficiency.
Pin Routes, CACI’s route optimisation software, is designed to help organisations cut costs, navigate uncertainties and increase efficiency, so that these rising costs have less of an impact. Pin Live, our delivery and collection management software, helps drivers take the correct detour and improve last-minute decision-making when changes arise on the road. Together, these tools help logistics leaders improve route compliance and maintain predictable operations despite market uncertainty.
To learn more about how CACI can help your organisation effectively navigate fuel volatility at cost, get in touch with us.
What is service design & how does it impact end‑to‑end performance?
Service design may be a familiar term among senior leaders, but clearly articulating what it means in practice can be a challenge. While awareness of service design is high, only around 3% can define it accurately, highlighting a long‑standing understanding gap.
Clarity around service design is imperative for performance. So, how does understanding the intricacies of service design impact your organisation’s end-to-end performance?
What is service design?
In commercial and operational terms, service design is the discipline of improving end‑to‑end service performance. It aligns the entire service ecosystem, people, processes, technology, data, policy and experience, ensuring services function accordingly.
Where a UX designer focuses on research and purely digital components like websites, a service designer will consider all touchpoints (telephony, physical spaces, technology infrastructure, etc.) for both its users and employees, discovering and fixing pain points.
Service design is:
Understanding how a service works today (across frontstage and backstage)
Identifying what users need and where the service breaks down
Designing how the service should work: consistently, efficiently and at scale
Aligning digital, operations and experience into a unified service model
Creating a roadmap that is actionable, measurable and ready for delivery
Service design is not:
Just journey mapping
An isolated discovery exercise
A purely creative or theoretical activity
A handover document expecting someone else to deliver it
A UX‑only discipline
At its core, service design is about making services more efficient for end-to-end customers users and the teams delivering them while enabling growth.
Understanding the impact of service design on end-to-end performance
While service design has become popularised across digital transformation, customer experience, and operational change, understanding its place (whether it mirrors journey mapping or UX), where it fits within your organisation’s objectives and whether it will improve performance remain in question.
Many organisations invest in fragmented discovery work, generate compelling artefacts and still struggle to fix the operational issues that matter. This deduces service design to a capability, not a driver of performance.
Meanwhile, AI is accelerating change faster than most companies can absorb. Nearly two‑thirds of organisations yet to scale AI effectively, emphasising the need for a clear, practical and end‑to‑end approach to service design. When service design is poorly understood, opportunities are missed along with potential performance gains. When integrated from discovery through to delivery, organisations see:
Modernise faster with less rework
Adapt to market disruption
Reduced programme risk and operational waste through meaningful change that sticks
Deliver services that are easier for users and more efficient for teams
Cut costs to unlock value across your entire service ecosystem.
Service design is more than just a way to fix broken experiences. It is a strategic lever for growth, efficiency, resilience and competitive advantage.
How CACI enables service design built for implementation
At CACI, service design begins the moment insight turns into direction. Unlike traditional models where discovery and delivery sit far apart, our approach embeds service design thinking directly into the core functions that drive change. From data and analytics to digital engineering, architecture, technology delivery, operational transformation, change management and programme assurance.
By integrating these capabilities, we remove the gaps and hand‑offs that typically slow organisations down. It means the services we design can be implemented without translation, the solutions we deliver are measurable from day one, and the insights we capture continually feed improvement. Ideas don’t get diluted as they move downstream, they gain momentum.
Why this matters for modern organisations
Leaders typically operate in environments defined by rising expectations, increasing complexity, legacy constraints and mounting pressure to deliver seamless, reliable and efficient services.
Service design plays a critical role in enabling this by helping organisations:
Align services with strategic intent, policy goals or commercial outcomes
Improve operational performance and reduce friction across journeys
Deliver measurable, user‑centred improvements that stand up to scrutiny
Modernise processes and technology to unlock value from existing and future platforms
Strengthen accessibility, compliance, trust and resilience
Enable data‑driven transformation that can scale across teams and channels
CACI’s integrated model blends service design, research, data, engineering and delivery to translate insights into meaningful operational change. Organisations across complex, high‑stakes environments rely on CACI to redesign, modernise and optimise the services that matter most, improving experience, reducing cost‑to‑serve and accelerating performance through practical, evidence‑led transformation.
Organisations in complex, high‑stakes environments work with CACI to address root‑cause issues across their services, improving experience, reducing operational cost and driving performance gains that hold up in delivery.
This year’s MCA Food to Go conference unveiled the key growth drivers, future trends and exciting developments shaping the sector. It highlighted everything from innovative technology and formats to trendsetting menus and marketing, ultimately exploring how successful brands are navigating market challenges.
At the conference, I showcased transaction trends and growth opportunities emerging in 2026 based on three months of data from CACI’s Brand Dimensions dataset. By tracking 30+ food to go brands from November 2025 to January 2026, I assessed the trends and opportunities fuelling growth questions this year.
Here is what the data revealed.
Food to Go transaction trends & growth opportunities in 2026
The findings showed:
+6% YoY revenue growth in the Cafés & Coffee Shop market
A slight decrease in Quick Service Restaurant (QSR) transactions, but a slight increase in Average Transaction Value (ATV)
Transactions and revenue dropping across the wider F&B sector
Which brands are leading industry trends in 2026?
From the 30+ up-and-coming and major players in the food to go sector tracked, I identified the leading brands as those achieving YoY growth above inflation and sorted them by increase in growth percentage.
Premium healthy lunches: Atis & Farmer J
Consumers continue to prioritise premium healthy lunches this year.
The leading brands were Atis, growing 140%, and Farmer J, growing ~30%. Atis’ skyrocketing growth is driven by the opening of a third new space in the last year. While substantial and impressive, it is the smallest brand in CACI’s Food to Go tracker, meaning the overall GBP shift in the market is small.
The largest share of the customer mix for these brands comes from CACI’s Acorn profiles Prosperous Professionals at 15% of spendfollowed by Up-and-coming Urbanites at 11%.
For new entrants, the challenge to growth is proving value in each transaction, precise targeting and mission expansion without undermining the brand or cannibalising sales.
Continued growth in chicken QSR: Popeyes, Wingstop & Slims
Consumers continue to seek indulgence and novelty. In the chicken QSR sector, our findings concluded Popeyes grew ~30%, Wingstop ~20% and Slims ~9% (who were +46% in the first quarter of the year). While this may counter the premium healthy lunch trend, consumers are finding ways to balance health-conscious choices with indulgent ones.
Caffeine & matcha on the rise: Blank Street & Grind
Both Blank Street and Grind grew over 20%, indicative of the brands’ innovative products, strong social media presence and matcha-led menus. These brands have evidently appealed to younger, experience-driven consumers by creating excitement through their product innovation.
Established brands are driving growth by harnessing loyalty
The biggest takeaway is that while new entrants win on excitement, established brands win on loyalty.
New brands have brought excitement, and with that, percentage growth, but most saw YoY growth rates slow across the year. Meanwhile, more established brands like Pret a Manger, Costa, Starbucks and McDonald’s saw stronger growth in the latest quarter. When assessing actual pounds versus percentage growth, established brands are back growing and seeing very substantial sales gains. This reiterates the impact of loyalty on long-term growth.
The formula of the current state of the market then becomes:
New brands, social media influence and new cuisine are fuelling excitement. Loyalty is driven by familiarity, perceived value, brand resonance and communication. Brands that can achieve a sweet spot between both are poised for sustainable growth. However, our findings suggest tension between excitement and loyalty. This prompts brands to reflect on how to maintain excitement or build customer loyalty.
Four strategies to drive growth in a tough climate
1) Having the right products in place
Brands must understand how to appeal to existing customers and excite new ones. Product and menu innovation should be strategically considered to open new missions and tailor to the right locations, dayparts and missions.
2) Getting the right space
While growth can be achieved by acquiring new spaces, established brands are always optimising their spaces to reach the right people, in the right place, at the right time. This is why some brands are shifting to drive-through locations as town centres decline and why many have opted to offer FMCG products in the chilled sections of supermarkets.
3) Appealing to customers through the right message
Tailored content sent to the right target group at the right time with the right incentive is critical to success.
4) Delivering with the right service
Profitably staffing each location, determining which locations will best suit trialling self-service kiosks and avoiding alienating or upsetting customers who value your brand’s personal service are critical considerations.
This is often easier in the new entry “excitement” phase, but new and established entrants must constantly evaluate that they have the right mix of these factors to remain relevant in a rapidly changing market. Each of these strategies has a ‘people, place and time’ lever that can be pulled to maximise growth by leveraging customer loyalty.
How CACI’s Brand Dimensions can help your Food to Go business thrive
With so much complexity in the food to go sector, brands need more than just internal customer data to keep on top of the mix. Supplementary market data through CACI’s Brand Dimensions can help you answer your growth questions, combining the right data with the right tools to project long-term growth through the right mix of products, services, places and messaging.
Highly detailed, timestamped transaction data is at the heart of Brand Dimensions, indicating anonymised customers and specific outlets to infill any data gaps and gain unique performance and competitor outlet insights.
When combined with anonymised mobile activity data and demographic classifications, it creates a cohesive base to address the people, place and time levers driving growth. This can also be topped off with lifestyle attributes linked to those demographics, competitor location data and competitor sentiment data.
Through this, businesses can better prepare for the future by understanding consumer behaviour at brand level.
Although Brand Dimensions is typically tracked on a monthly basis, these findings have been summarised quarterly for this blog.
If your brand could benefit from these data insights, book a Brand Dimensions demo with us.